

FD Reinvestment Risk: Causes, Examples and Ways to Manage It


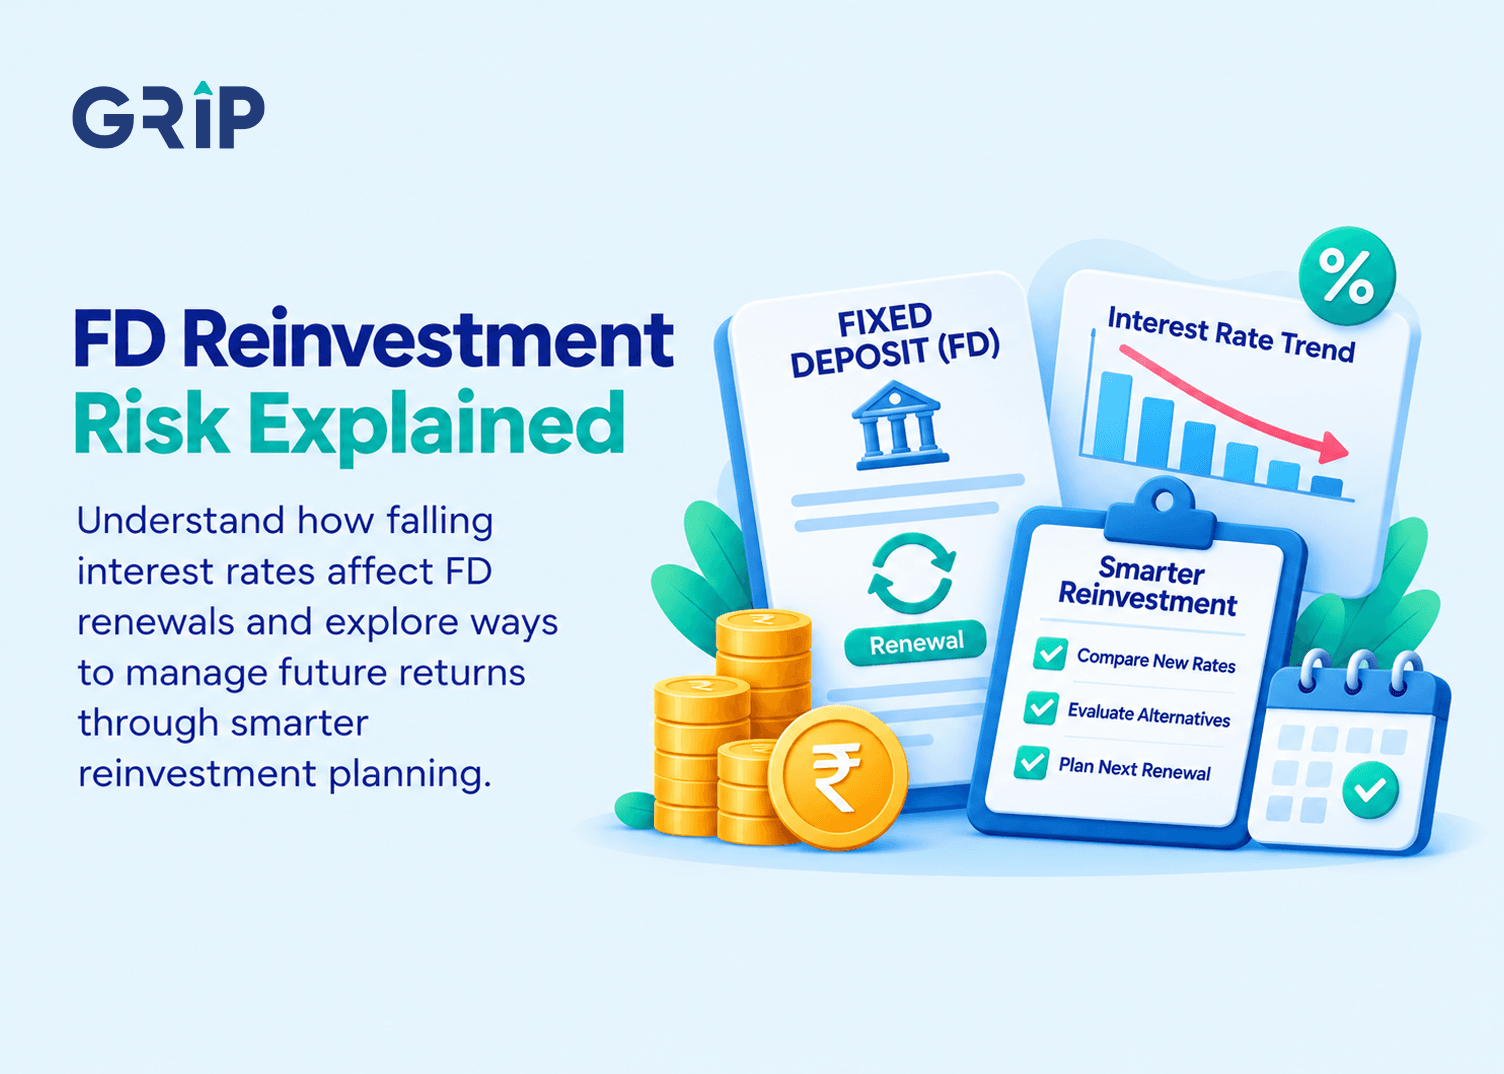
Fixed deposits (FDs) offer a way to earn interest at a predetermined rate over a selected tenure. However, you may not earn the same return over successive investment periods.
When an FD matures, the interest rates available for a new deposit may be lower than the original rate.
This creates FD reinvestment risk, where renewing a deposit at a lower interest rate can reduce future earnings. Understanding why this happens, how it affects long-term income, and what investors can do to manage it can support better financial planning.
What Is Reinvestment Risk in Fixed Deposits?
Reinvestment risk in fixed deposits is the possibility of earning lower returns when the maturity proceeds or interest payments from an existing FD are reinvested at a lower rate.
While the principal amount remains available for fixed deposit reinvestment, the income it generates changes. This risk becomes more relevant if you frequently renew your FDs or depend on interest income.
For instance, let’s assume that you invest in a 3-year FD at 7.5% interest. The going rate could be down to 6% when the deposit matures. If you renew the FD, the new deposit will earn less interest than the original deposit.
How Does Reinvestment Risk Affect FD Investors?
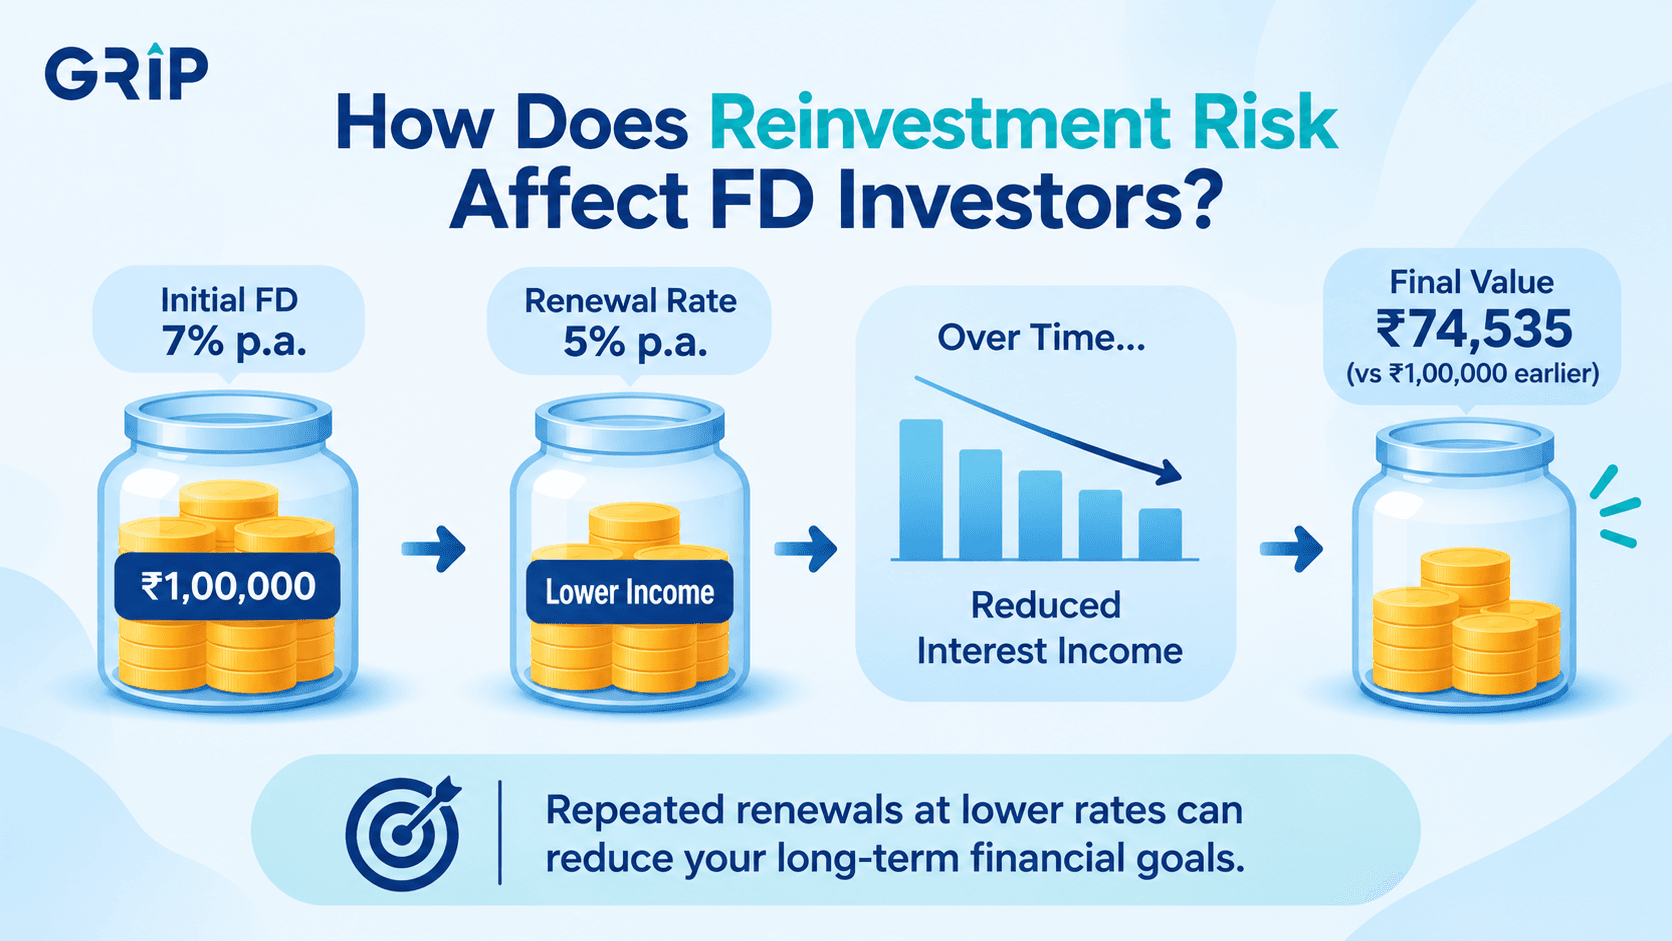
Reinvestment risk can affect both the income on deposits and the total amount built up over time. The impact is more pronounced if investors continue to renew their FDs repeatedly even with falling interest rates.
Suppose there is an investor who has FD interest as a regular source of income. If the FD renewal interest rates available are lower when it matures, the interest earned during the next tenure also goes down. By practising this over and over, you slowly eat away at the income you get from the original principal.
It can also impact financial objectives in the long term. Fixed deposits have gained popularity as a form of investment. But investors who keep renewing at lower rates may find they are getting less than they expected. This may result in a discrepancy between the anticipated fixed deposit maturity value and the actual accumulated amount.
What Causes Reinvestment Risk In Fixed Deposits?
Several market and economic developments can influence the interest rates available when an FD matures.
- Falling interest rates: When market interest rates decline, new deposits may offer lower returns than existing FDs. Investors renewing their deposits may therefore have to accept a lower rate.
- Monetary policy changes: Central bank decisions can influence interest rates and borrowing costs. Monetary policy changes can affect the rates offered on new fixed-income investments.
- Economic cycles: Changes in economic growth, inflation and credit demand can influence market interest rates and the returns available on new investments.
- Changing market conditions: Market developments can affect the availability of suitable investment options and the rates investors can obtain when reinvesting.
The common factor is that the interest rate available at fixed deposit maturity may differ from the rate secured when the original FD was opened.
Reinvestment Risk vs Interest Rate Risk
Reinvestment risk is the risk of earning lower returns on interest or maturity proceeds when reinvesting. Interest rate risk is the risk of changes in an investment’s market value due to interest rate movements. Both have to do with changes in interest rates, but they affect investments differently.
Basis | Reinvestment Risk | Interest Rate Risk |
Main concern | Future income from reinvested money | Change in the value of an existing investment |
When it becomes relevant | When an investment matures or pays interest | When market interest rates change |
Impact | Lower returns on subsequent investments | Potential changes in the market value of existing fixed-rate securities |
For FD investors, reinvestment risk matters most when renewing a deposit at a lower rate. FD interest rate risk, meanwhile, concerns changes in the market value of existing fixed-rate securities.
Inflation risk is another distinct concern. While fixed deposit reinvestment risk relates to the interest available on a new deposit, inflation can erode purchasing power over time. These risks should not be treated as interchangeable.
Example Of Reinvestment Risk In Fixed Deposits
Let's understand reinvestment risk in fixed deposits with the help of an example. Let's assume that you deposited INR 1,00,000 in an FD for three years at an annual interest rate of 7.5%. At maturity, you reinvest the entire amount for another three years.
However, the available FD renewal interest rate has fallen to 6%. You will now earn a lower return over the subsequent tenure.
The following comparison illustrates how the two rates affect the maturity value.
Illustrative comparison:
Renewal rate | Maturity value |
7.5% per annum | INR 1,24,230 |
6% per annum | INR 1,19,102 |
Note: For the sake of the illustration, it is assumed that the FD is compounded annually, with no additional deposits or withdrawals. Further, the illustration excludes applicable taxes.
The difference is approximately INR 5,128. This shows how a lower FD renewal interest rate can reduce the amount accumulated over the next three years, even when the original principal is fully reinvested.
How To Manage Reinvestment Risk In FDs
If you want to reinvest your FD, you cannot totally eliminate the reinvestment risk. But you can plan your deposits to manage your exposure to changing interest rates.
1. Consider FD laddering: Spread your money over deposits with different maturity dates. This spreads the reinvestment decision out over time, rather than having the entire amount dependent on the rates available on any one day. Laddering however does not ensure good renewal rates.
2. Review maturity dates: Keep track of when each FD matures so that reinvestment decisions are not left until the last moment.
3. Compare prevailing rates: Check the rates available when an FD matures rather than automatically renewing it at the same rate.
4. Consider cumulative FDs: These options put interest back into the deposit rather than paying it out periodically. This reduces the need to reinvest each interest payment, though the principal payment may still have reinvestment risk.
5. Consider future cash requirements: Consider the maturity dates of deposits in relation to expected needs for funds. This can help you decide if you want to reinvest the proceeds or keep them liquid for expenses that are coming up.
6. Review tax implications: Consider applicable taxes when assessing FD returns and deciding how much to reinvest.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


