

Company Fixed Deposits: Features, Returns, Risks And How To Choose


When it comes to fixed-income investments, bank fixed deposits (FDs) have long been a preferred choice for investors living in India. They are offering predictable income, stable returns, and also a sense of security.
Moreover, with changing interest rates, various investors are looking for various options that can generate higher returns without taking excessive risks.
One such investment is a Company Fixed Deposit (Company FD).
At first glance, the interest rate is high which is offered by company fixed deposits as it may seem highly attractive. But before investing, it is essential to ask a few questions:
- Are company fixed deposits safe?
- Why do companies offer higher interest rates?
- How can you identify a reliable company?
- Are the returns worth the additional risk?
Understanding the answers that can assist you to make a smarter investment decision instead rather than simply chasing the high percentage of returns.
What Is a Company Fixed Deposit?
A Company Fixed Deposit defines the fixed-income investment where you lend money directly to a company for a particular period of time. In return, the company agrees to pay a fixed interest rate and return your principal amount on maturity.1
Unlike a bank FD, where your money is deposited with a bank, a company FD is issued by companies such as:
- Non-Banking Financial Companies (NBFCs)
- Housing Finance Companies
- Manufacturing Companies
- Large Corporate Businesses1
These organisations use the money raised from investors for many business purposes and reward investors with comparatively higher interest rates.
Most company fixed deposits provide:
- Fixed investment tenure ranging from 1 to 5 years
- Guaranteed interest rate throughout the tenure
- Monthly, quarterly, annual, or cumulative payout options
- Flexible minimum investment amount
The biggest attraction is that company FDs generally offer better returns than many traditional bank FDs just because investors take slightly higher credit risk.
Why Do Companies Raise Money Through Fixed Deposits?
Many people assume companies issue fixed deposits only because they cannot obtain bank loans. In reality, even financially strong companies use company fixed deposits as part of their funding strategy.
Here are some major reasons and these are:
1. Business Expansion
Companies often need funds to expand operations.
For illustration, a manufacturing company planning to build a new plant or launch products in new cities requires significant capital. Raising money through company fixed deposits helps finance these projects while reducing dependence on bank loans.
Successful expansion can improve business performance, making it easier for the company to meet its repayment commitments.
2. Managing Working Capital
Every business requires funds for day-to-day operations.
Money raised through company deposits may be used for:
- Purchasing raw materials
- Paying salaries
- Maintaining inventory
- Managing operating expenses
- Meeting seasonal demand
For companies with stable cash flows, this becomes an efficient financing option.
3. Refinancing Existing Debt
Companies sometimes replace expensive loans with lower-cost funding.
By issuing company fixed deposits at competitive rates, businesses can reduce borrowing costs and improve profitability.
However, investors should evaluate whether the company is refinancing responsibly or struggling with excessive debt.2
4. Funding Long-Term Projects
Infrastructure, manufacturing, logistics, and housing finance companies often require large investments before projects begin generating income.
Company fixed deposits help finance:
- New factories
- Machinery purchases
- Renewable energy projects
- Technology upgrades
- Infrastructure development
Understanding how a company plans to use investors' money provides valuable insight into its financial strength.
Why Are Company FD Interest Rates Higher?
One of the biggest reasons investors consider company fixed deposits is their attractive returns.
Unlike banks, companies borrow directly from investors. Since these investments carry slightly higher credit risk, companies generally offer better interest rates as compensation.
Several factors influence company FD returns:
- Credit rating of the company
- Investment tenure
- Interest payout option
- Overall interest rate environment
Longer tenures often provide higher returns, while cumulative plans allow investors to benefit from the power of compounding.
However, remember that the highest interest rate is not always the best investment. Sometimes a company offering unusually high returns may also carry higher financial risk.
The next step is to evaluate the company's overall financial health before investing.
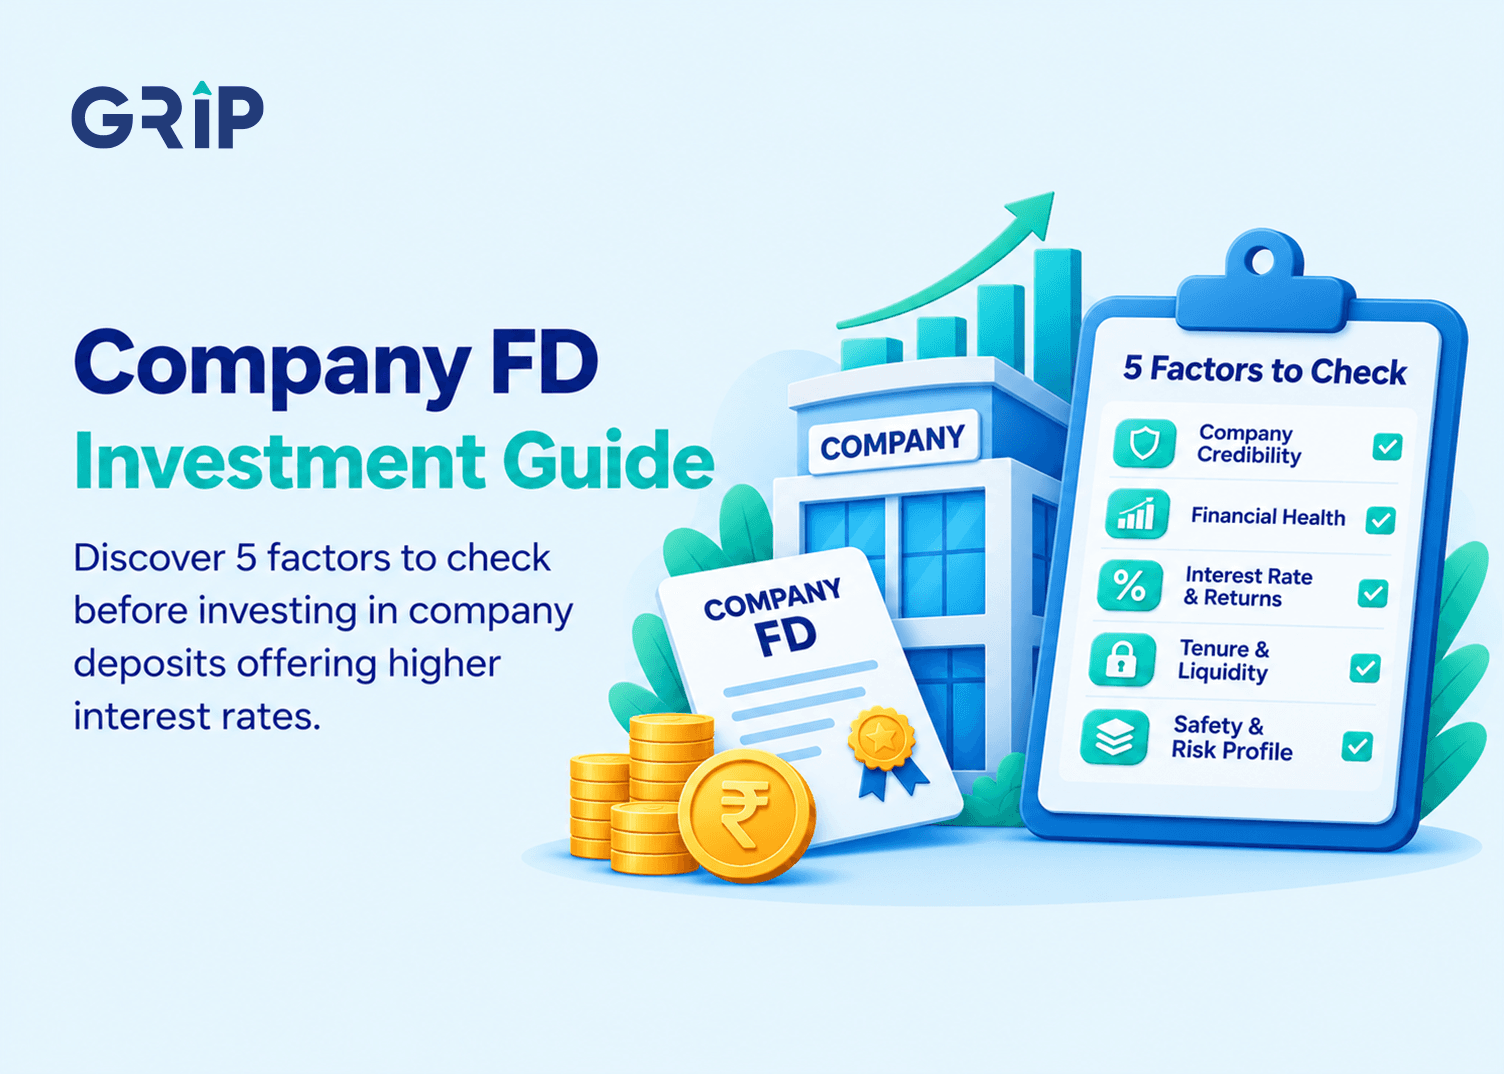
How To Evaluate A Company Before Investing
A higher interest rate may look attractive, but it should never be the only reason to invest in a company fixed deposit. The company's financial strength plays a much bigger role in determining whether your investment is safe.
Here are some key factors to check before investing.
1. Credit Rating
A company's credit rating indicates its ability to repay investors. Independent credit rating agencies assess the financial health of companies and assign ratings accordingly.
While no investment is completely risk-free, a higher-rated company generally has a stronger repayment capacity than one with a lower rating.
2. Debt Levels
Review how much debt the company already has. If borrowings are increasing while revenues remain flat, it may indicate financial stress.
Companies with manageable debt levels are generally in a better position to repay investors on time.
3. Profitability
Consistent profits are a positive sign of financial stability. Instead of looking at just one year's performance, check whether the company has maintained steady revenue and profit growth over several years.
A profitable business is more likely to meet its interest and maturity obligations.
4. Cash Flow
Profit figures don't always tell the complete story. A company should also generate healthy cash flows from its core business.
Strong cash flow means the company has enough liquidity to meet operational expenses and repay investors without financial pressure.
5. Repayment History
One of the simplest ways to judge a company is by looking at its repayment record. Companies that have consistently honoured previous fixed deposits build greater investor confidence than those with delayed repayments.
What Are The Risks Of Company FDs?
Although company fixed deposits can offer attractive returns, they also carry certain risks that every investor should understand.
- Default Risk
Unlike bank fixed deposits, company FDs are not backed by deposit insurance. If the issuing company faces financial difficulties, repayments may be delayed or, in rare cases, investors could face losses.
- Liquidity Risk
Many company FDs have lock-in periods or penalties for premature withdrawal. If you need your money urgently, accessing it may not be as easy as withdrawing a bank FD.
- Credit Downgrade Risk
A company's financial health can change during your investment period. If its credit rating is downgraded, it may indicate increasing financial stress and higher repayment risk.
- Concentration Risk
Investing your entire savings in one company fixed deposit increases risk. Diversifying your investments across different issuers and asset classes can help reduce the impact of any single investment underperforming.3
Company Fixed Deposit vs Other Fixed-Income Investments
Feature | Company FD | Bank FD | Corporate Bonds | Debt Mutual Funds |
| Returns | Generally Higher | Moderate | Varies | Market-linked |
| Risk | Moderate | Low | Moderate | Moderate |
| Capital Protection | Depends on Company | Higher | Depends on Issuer | Not Guaranteed |
| Liquidity | Moderate | High | Moderate | High |
| Suitable For | Investors willing to evaluate credit risk | Conservative investors | Experienced investors | Investors seeking diversification
|
Each investment option serves a different purpose. Choosing the right one depends on your financial goals, investment horizon, and risk appetite.
How To Decide If A Company Fixed Deposit Is Right For You
A company fixed deposit can be a good option if you're looking for predictable income and are comfortable taking slightly higher risk than a traditional bank FD.
However, it is not suitable for investors who prioritise maximum safety over returns. Instead of selecting a company FD solely because it offers the highest interest rate, take time to evaluate the issuer's financial position, credit rating, debt levels, and repayment history.
A well-researched investment is always better than chasing attractive returns without understanding the risks involved.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


