

SWP Taxation In India: How Are Systematic Withdrawal Plans Taxed?


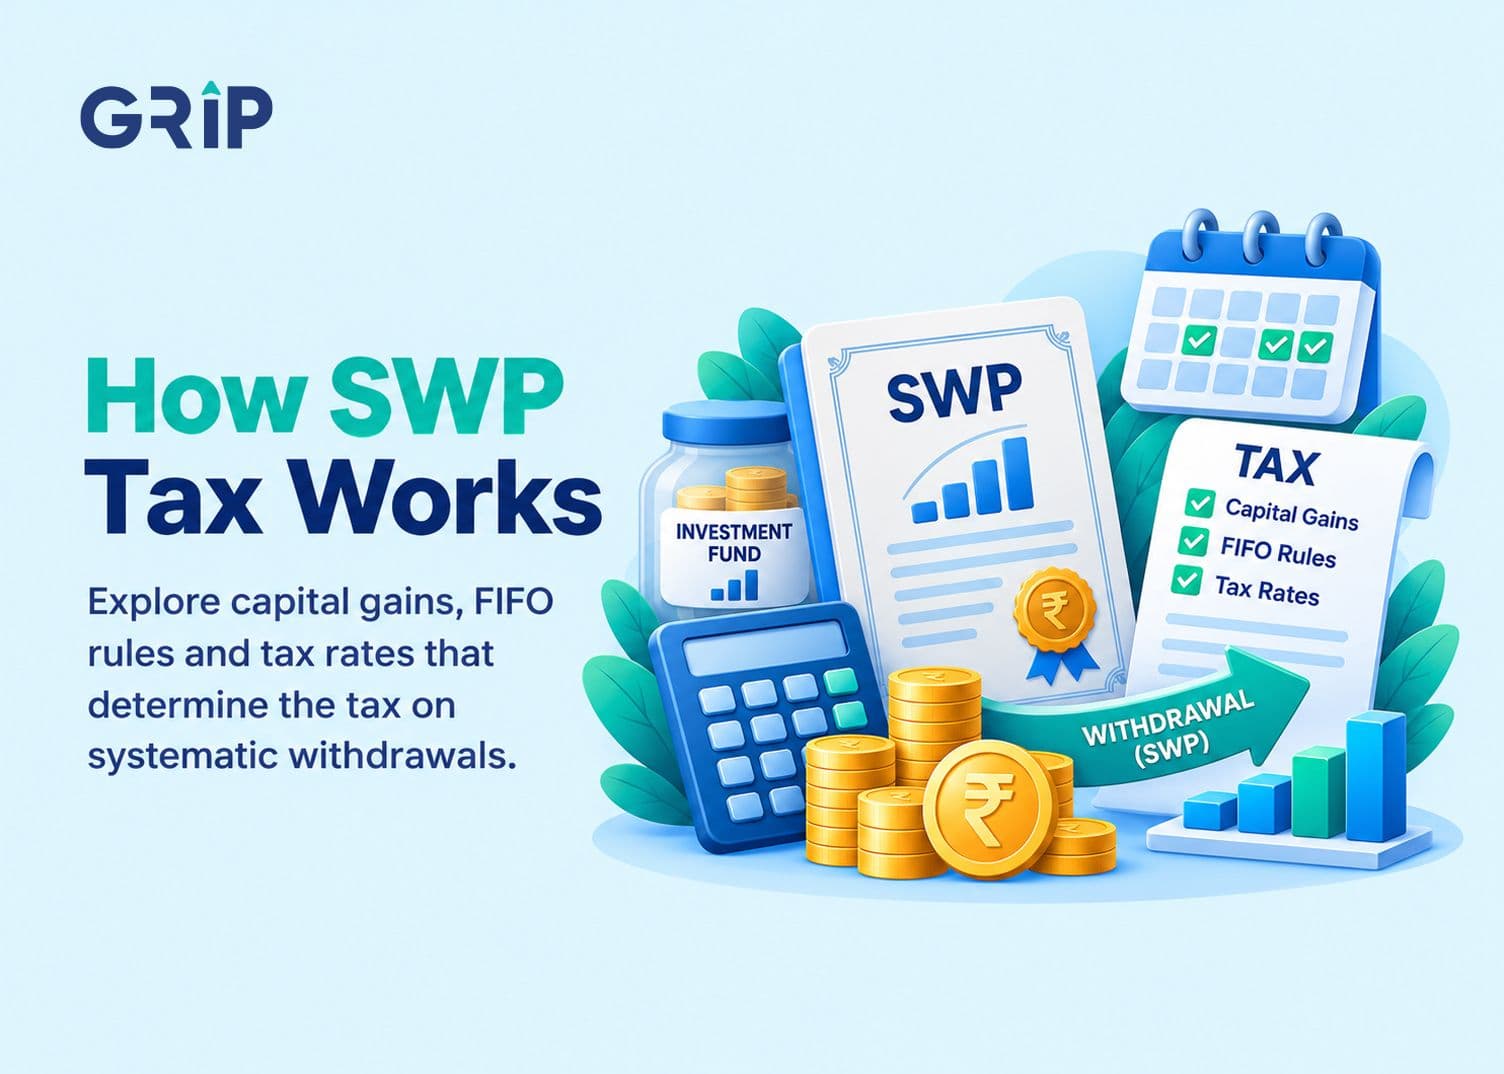
Every withdrawal from an SWP is not entirely taxable. When you withdraw money from a mutual fund, only the capital gains on the units redeemed are considered for taxation.
SWP Taxation depends on three factors- mutual fund type, how long you have held the units and the gains earned on them. Here is how the tax on SWP withdrawals is calculated under the FY 2026-27 rules in India.
What Is A Systematic Withdrawal Plan (SWP)?
An SWP facilitates withdrawing a fixed amount from an existing mutual fund investment at regular intervals, usually monthly or quarterly. Unlike a SIP, which involves periodic investments, an SWP involves regular withdrawals by redeeming mutual fund units at the prevailing Net Asset Value (NAV).
For example, suppose an investor has INR 5 lakh invested at an NAV of INR 50, holding 10,000 units. They start a monthly SWP of INR 10,000. Here is how the SWP works over five months:
Month | NAV (INR) | Units Redeemed | Remaining Units |
|---|---|---|---|
January | 50 | 200 | 9,800 |
February | 52 | 192.31 | 9,607.69 |
March | 48 | 208.33 | 9,399.36 |
April | 50 | 200.00 | 9,199.36 |
May | 55 | 181.82 | 9,017.54 |
As NAV changes, the number of units redeemed changes, even though the monthly withdrawal remains INR 10,000. For example, in January, INR 10,000/ INR 50 = 200 units redeemed, whereas when NAV was INR 52, approx. 192 units were redeemed.
How Is SWP Taxed In India?
SWP withdrawals attract capital gains tax only on the gains earned from redeemed mutual fund units, not the entire withdrawal amount. If the redemption results in a loss, no SWP capital gains tax arises on that transaction.1
The following three factors generally determine SWP tax in India:
| Factor | How it affects taxation |
| Purchase cost | Capital gain is the difference between the redemption value and the cost of units sold, after eligible adjustments. |
| Holding period | How long you hold the units decides whether the gain is short-term (STCG) or long-term (LTCG), depending on the fund. |
| Fund category | Equity, specified debt and other mutual funds follow different tax rules. |
Redemptions generally follow the first-in, first-out (FIFO) method. Here the units purchased earliest are redeemed first. Now, consider someone who bought mutual fund units in January and again in June. If they start an SWP in October, the January units are generally sold first. Their original purchase cost and holding period are used to calculate capital gains and determine whether they fall under STCG or LTCG.
SWP Taxation Based On Mutual Fund Categories
The applicable systematic withdrawal plan taxation for resident individuals in FY 2026-27:
| Fund category | Holding period | Gain type | Tax rate |
| Equity-oriented funds | Up to 12 months | STCG | 20% |
| Equity-oriented funds | More than 12 months | LTCG | 12.5%* |
| Specified debt funds acquired from 1 April 2023 | Any duration | Deemed STCG | Slab rate |
| Older debt investments and other unlisted non-equity funds | Up to 24 months | STCG | Slab rate |
| Older debt investments and other unlisted non-equity funds | More than 24 months | LTCG | 12.5% |
| Listed non-equity funds, such as gold ETFs | Up to 12 months | STCG | Slab rate |
| Listed non-equity funds, such as gold ETFs | More than 12 months | LTCG | 12.5% |
Source: Income Tax India2
Equity LTCG rate applies to aggregate eligible gains exceeding INR 1.25 lakh per tax year. Rates exclude applicable surcharge and cess.
How To Calculate Tax On SWP Withdrawals?
Consider Parag Parikh Flexi Cap Fund (Direct Growth), India's largest active equity fund by AUM in September 2026.
Suppose an investor invested INR 5,00,000 on 29 December 2023 at NAV INR 70.2435. They start a monthly SWP of INR 1,000 on 15 September 2026.3
SWP tax calculation for September:
- September NAV= INR 89.3125
- Units redeemed= 1000/89.3125 = 11.1966
- Original cost= 11.1966*70.2435 = INR 786.49
- Capital gain= 1000 ? 786.49 = INR 213.51
Particulars | September 2026 | October 2026 |
NAV (INR) | 89.3125 | 90.6040 |
Units redeemed | 11.1966 | 11.0370 |
Original cost (INR) | 786.49 | 775.28 |
Capital gain (INR) | 213.51 | 224.72 |
Source: PPFAS4,5
The investor withdraws INR 2000, but earns only INR 438.23 in capital gains.
The possible mutual fund SWP taxation scenarios are:
- No tax: If annual eligible equity LTCG stays below INR 1.25 lakh, no LTCG tax applies.
- Tax payable:
If the investor has already earned INR 1,30,000 in eligible equity LTCG from other investments during that tax year, the SWP gains will increase the total taxable amount.
- Total LTCG= INR 1,30,000 + INR 438.23= INR 1,30,438.23
- Taxable LTCG= INR 1,30,438.23? 1,25,000= INR 5,438.23
- LTCG tax at 12.5% = INR 679.78
- Cess at 4%= INR 27.19
- Total tax payable= INR 707
SWP Taxation Vs SIP Taxation
An SIP involves investing money regularly; on the opposite, SWP involves withdrawing it. The difference in taxation comes down to when mutual fund units are sold.
| Basis | SIP | SWP |
| Transaction | Purchase of mutual fund units | Redemption of mutual fund units |
| When tax applies | When units are redeemed, not when invested | On capital gains from each withdrawal |
| Holding period | Calculated separately for each SIP instalment | Based on the purchase date of units redeemed |
| Tax rates | Depend on fund category and holding period | Depend on fund category and holding period |
Both follow the same capital gains tax rules. However, SIP investments create different purchase lots, each with its own holding period. When these units are redeemed, the FIFO method determines which units are sold first.
Factors To Consider Before Starting An SWP
If one is considering an SWP, take note of the following:
- Withdrawal amount: Choose an amount based on your expenses and available corpus. For instance, INR 20,000 per month from INR 10 lakh means withdrawing 24% of the starting investment annually. This may be difficult to sustain.
- Market dynamics: If markets fall, more units must be sold to maintain the same payment. Fewer units remain invested when markets recover.
- Charges: Check the fund's exit-load period. Redeeming units too early can mean paying an extra charge.
- Taxes: Assess the gains on units due for redemption. Include other capital gains when calculating your annual tax liability.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


