

SIF Taxation In India 2026: Tax On Specialised Investment Funds Explained


How Is SIF Taxed In India?
Specialised Investment Funds, or SIFs, are mutual fund schemes offering more specialised investment strategies. The tax on SIF is based on the SIF structure, investment strategy and applicable income-tax provisions. This means Specialised Investment Fund taxation does not apply to a specific tax rate.
For instance, if an SIF framework is equity-oriented, the short-term capital gains on units held for up to 12 months are taxed at 20% and the long-term capital gains on units held for more than 12 months are taxed at 12.5% without indexation on gains exceeding INR 1.25 lakh in a financial year.1
The applicable tax can differ where an SIF follows a different investment strategy or holds assets with different tax treatment. In case of distributions, where applicable, this may also be taxable separately at the applicable slab rate of the investor.
Investors should therefore refer to the latest scheme documents and applicable income-tax provisions before calculating their SIF tax liability.
SIF Taxation On Income Distribution
Income distributed under an SIF, including an IDCW distribution, is taxable in the hands of the investor. This is part of the SIF tax treatment for distributed income. For resident investors, the income is taxed at the applicable income-tax slab rate, along with surcharge and cess, where applicable.2
TDS is also applicable on the income distributed to the resident investors at the rate of 10% if the total amount is more than INR 10,000 in a financial year. In the case of non-resident investors, TDS may apply at 20%, subject to the relevant tax provisions and DTAA benefits.
The tax on SIF distributions therefore depends on the residential status and the applicable tax rules of the investors.
Further, it is also important to note that TDS is not the final tax liability. The TDS deducted can be claimed as a tax credit against the actual tax payable while filing the income-tax return. The final liability depends on the applicable tax rate and the investor’s total taxable income.
Tax Treatment of SIF vs Bonds
The bonds and SIF tax treatment differs based on their structure and underlying investments.
Here are the key differences:
Features | Specialised Investment Funds (SIFs) | Bonds |
| Fund/Internal Activity | Income earned by the SIF is generally exempt at the fund level under applicable mutual fund tax provisions. | Not applicable because the investor owns the bond directly. |
| Periodic Payouts | IDCW/distributions are taxed at the applicable individual tax rate. | Interest income is taxed at the applicable individual tax rate. |
| Short-Term Capital Gains | 20% for qualifying equity-oriented SIFs. Tax treatment for other SIF strategies depends on their classification under the applicable tax provisions. | Listed bonds held for 12 months or less are generally taxed at the applicable rate. Unlisted bonds are treated as short-term irrespective of the holding period. |
| Long-Term Capital Gains | 12.5% for qualifying equity-oriented SIFs held for more than 12 months. For other SIF strategies, the treatment depends on the fund’s classification and applicable holding-period rules. | Listed bonds held for more than 12 months are generally taxed at 12.5% without indexation. Unlisted bonds do not qualify for long-term capital gains treatment and are treated as short-term irrespective of the holding period. |
| Tax-Free Varieties | No tax-free SIF category is currently available. | Interest on certain notified tax-free bonds can be exempt, although capital gains on their transfer may still be taxable. |
Source: SEBI, Income Tax India3,4
How To Calculate Post-Tax SIF Returns
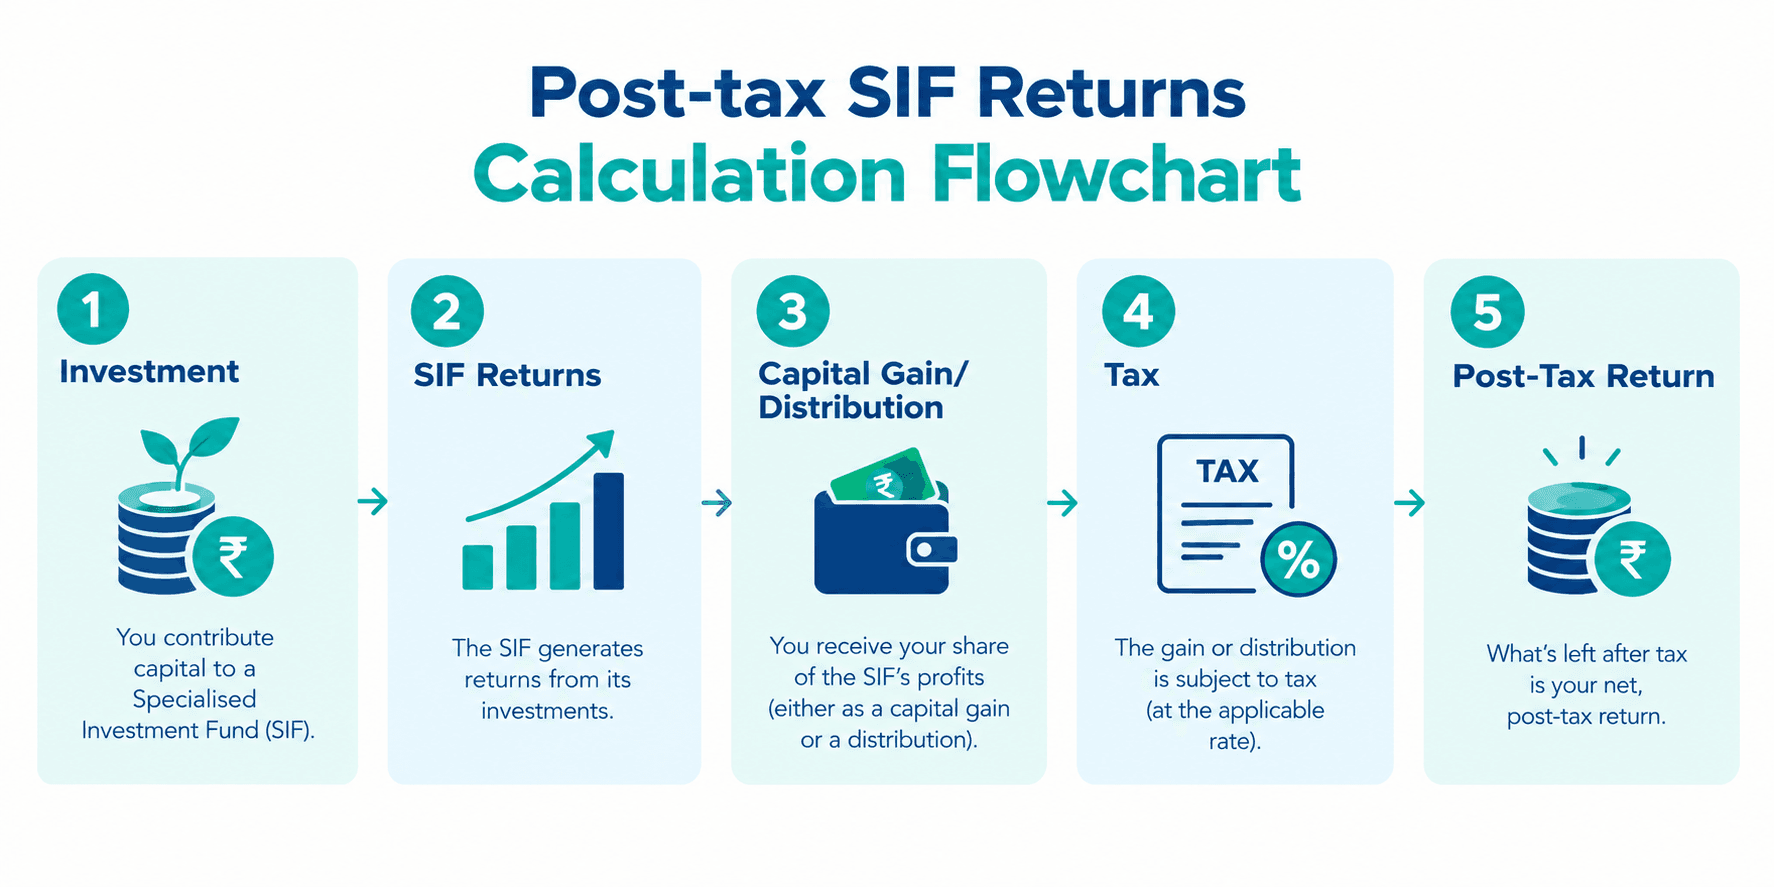
Post-tax returns show how much of your SIF earnings remain after paying the applicable tax. Here is how you can calculate it:
- Calculate investment return: Determine the value of your SIF investment at the end of the relevant period and calculate the total gain or distribution received.
- Identify income type: Separate the capital gains from distributions, as different tax provisions may apply to each type of income.
- Determine taxable amount: Calculate the tax based on the SIF strategy, holding period, investor status and applicable income-tax provisions.
- Calculate tax liability: Apply the applicable tax rate to the taxable capital gain or distribution, along with applicable surcharge and cess, where relevant.
- Calculate post-tax return: Subtract the actual tax liability from the gross gain and divide the resulting post-tax gain by the original investment to calculate the post-tax return percentage.
Note that you should not compare SIFs only on their pre-tax returns. Two SIFs with similar gross returns can produce different post-tax returns because their investment strategies and SIF capital gains tax treatment may differ.
SIF Taxation For Different Investor Categories
SIF mutual fund taxation differs based on both the investment strategy and the investor’s residential status. The tables below illustrate the treatment for an equity-oriented SIF.5
Resident Investors:
Income Type | Tax Treatment |
| Short-Term Capital Gains (Up To 12 Months) | Taxed at 20% |
| Long-Term Capital Gains (> 12 months) | Taxed at 12.5% on gains exceeding INR 1.25 lakh in a financial year, without indexation. |
| IDCW | Taxed at applicable income-tax slab rate |
| TDS on Income | 10% TDS when the total income distributed exceeds INR 10,000 in a financial year. |
Non-Resident Investors:
Income Type | Tax Treatment |
| Short-Term Capital Gains (? 12 months) | Taxed at 20% |
| Long-Term Capital Gains (> 12 months) | Taxed at 12.5% on gains exceeding INR 1.25 lakh, without indexation or foreign-exchange fluctuation benefit. |
| IDCW | Taxed at 20% |
| TDS on Income | 20% TDS or the lower DTAA rate, subject to applicable conditions and a valid Tax Residency Certificate. |
For non-resident investors, tax may also be withheld on capital gains at redemption at the applicable rates, subject to the relevant tax and treaty provisions.
What Should Investors Check Before Investing In An SIF?
Here are a few factors to check before you invest in a SIF:
- Investment Strategy: Check the investment objective, asset allocation and use of derivatives of the SIF. Some strategies can take unhedged short positions of up to 25%, which can increase losses when markets move against the position.6
- Liquidity Terms: Check the redemption frequency, notice period, exit load and minimum holding requirements. Some SIF strategies may require investors to provide a redemption notice of up to 15 working days.7
- Risk Level: Review the riskometer of the fund and understand the risks arising from derivatives, short positions, concentration and market movements. Higher strategy complexity can also increase the potential for capital losses.
- Fund Manager: Review the fund manager’s experience with the SIF strategy and assess whether its investment approach, risk level and expected holding period suit your financial objectives.
Conclusion
SIF taxation depends on the investment strategy, nature of income, holding period and investor status. Capital gains, distributions and TDS can therefore have different tax implications. Therefore, before investing, review the scheme documents, applicable tax provisions, liquidity terms and risk profile to assess the potential post-tax outcome.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


