

Bond Barbell Strategy: How It Works And How To Build One


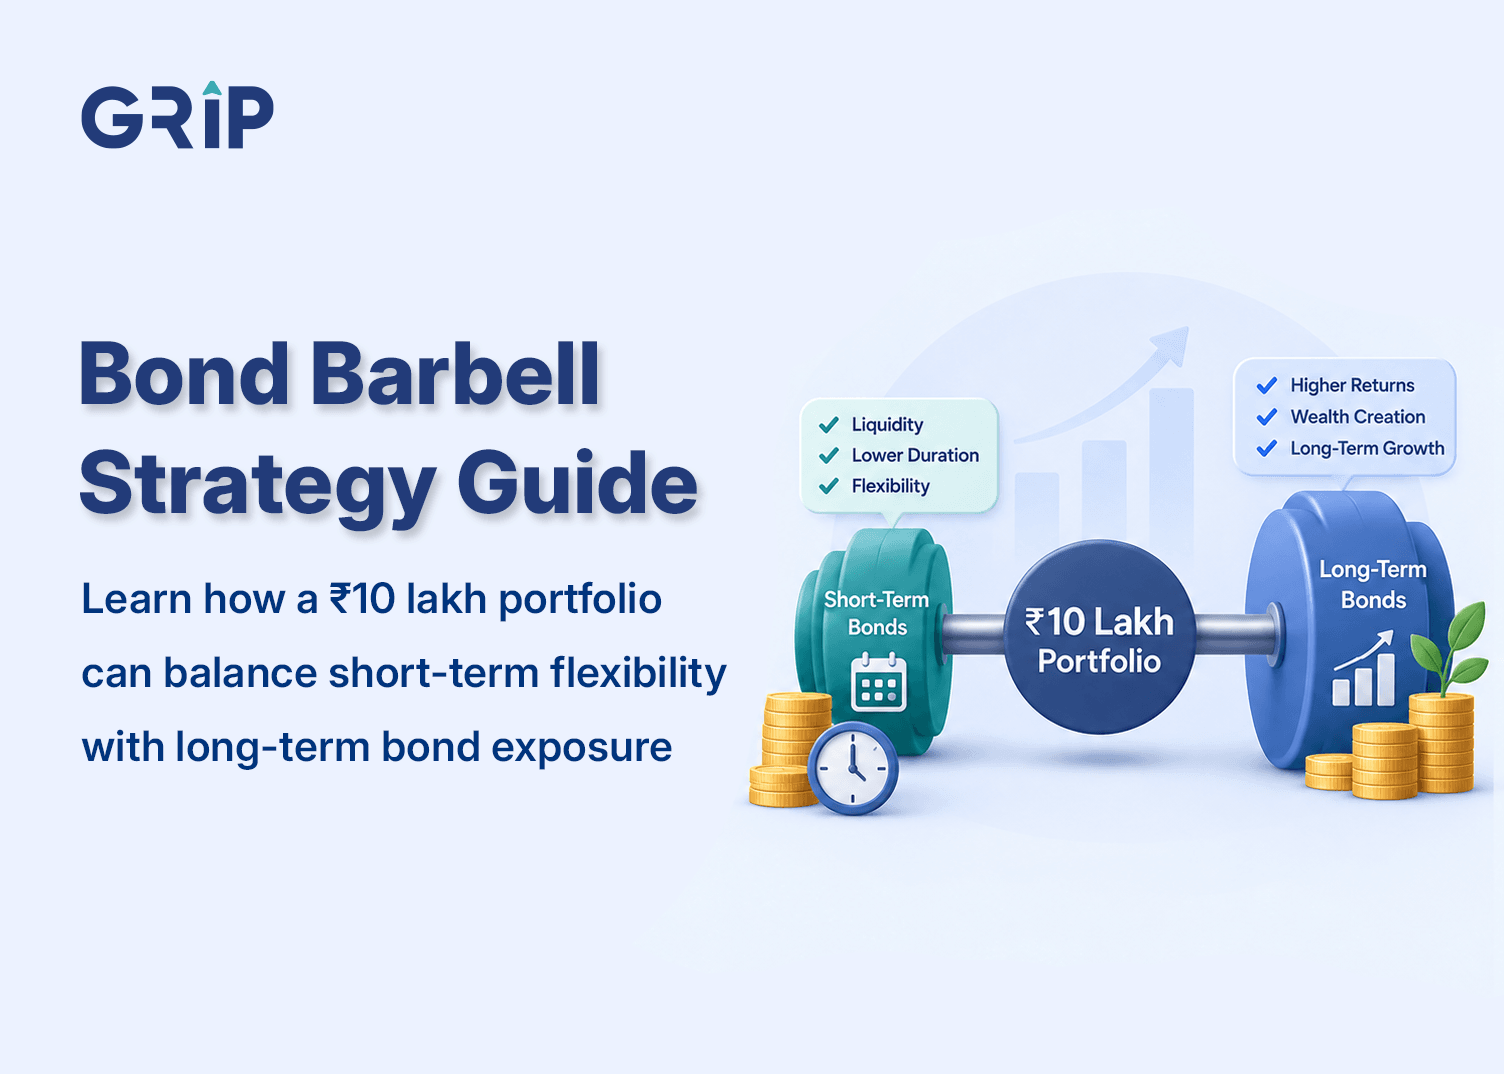
What if you could keep part of your bond investment relatively flexible while also locking in money for a long period of time? A Bond Barbell Strategy is designed around this idea. It divides a fixed-income portfolio which is mainly between short-term and long-term bonds, with limited exposure to medium-term bonds.1
This kind of strategy gives each side a different purpose. Short-term bonds can provide earlier access to maturity proceeds, while long-term bonds offer longer-duration exposure and that can lock in yields for an extended period. Moreover, investors are also required to consider interest-rate, reinvestment, credit and liquidity risks.
What Is A Bond Barbell Strategy?
A Bond Barbell Strategy is a bond investment approach where the portfolio is concentrated around two maturity segments: short-term and long-term bonds.2
Lets understand with an example- an investor could hypothetically divide INR 10 lakh equally between short-term and long-term bonds. This 50:50 split is only an illustration and should not be treated as a universal recommendation.
The strategy gets its name just because the portfolio resembles a barbell, with investments concentrated at both ends rather than distributed evenly across maturities.
The short-term portion can mature sooner, by giving investors an opportunity just to use the money or reinvest it on the basis of prevailing market conditions. The long-term portion remains invested for a long period of time and generally it has greater sensitivity to interest-rate changes.
How Does A Bond Barbell Strategy Work?
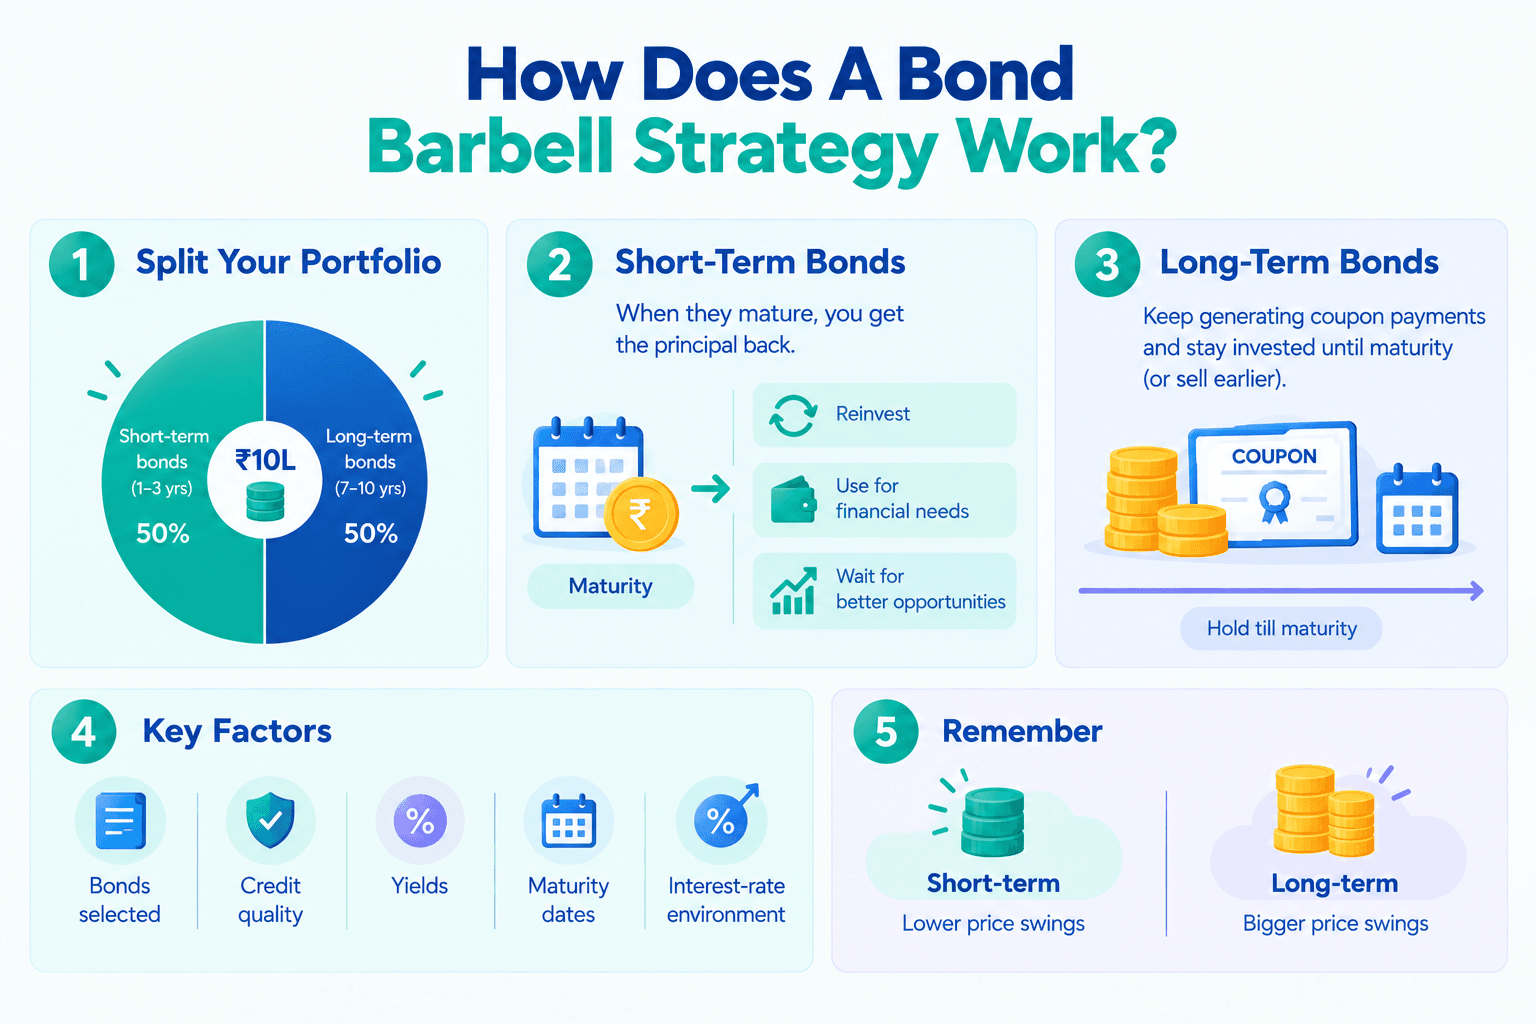
The barbell strategy in bonds works by combining two different maturity profiles.
Consider a INR 10 lakh portfolio split between short- and long-term bonds. When the short-term bonds mature, the investor receives the principal and can decide whether to reinvest it, use it for a financial requirement or wait for better market opportunities.
Meanwhile, the long-term bonds continue to generate their scheduled coupon payments and remain invested until maturity unless sold earlier.
This structure can provide flexibility while maintaining exposure to longer-term bonds. Moreover, the outcome depends on factors such as the bonds selected, their credit quality, yields, maturity dates and interest-rate environment.
Long-term bonds generally experience larger price movements when interest rates change. Therefore, investors should understand that the two sides of the barbell behave differently.
Why Do Investors Use A Bond Barbell Strategy?
One major reason investors consider a fixed-income barbell strategy is flexibility.
The short-term portion can mature earlier, allowing investors to reassess their investment decisions more frequently. If interest rates change, maturing funds can potentially be reinvested at prevailing rates.3
The long-term portion serves another purpose. It allows investors to maintain exposure to longer maturities and potentially lock in the available yield for a longer period.
A barbell can also spread maturity exposure between two ends instead of putting the entire portfolio into one maturity segment.
However, these benefits depend on the bonds selected, market conditions and portfolio management. A barbell does not eliminate investment risks or guarantee higher returns.
Short-Term Bonds Vs Long-Term Bonds In A Barbell Portfolio
The two portions of a barbell portfolio have different roles.
| Feature | Short-Term Bonds | Long-Term Bonds |
| Maturity | Earlier | Later |
| Interest-rate sensitivity | Generally lower | Generally higher |
| Main role | Flexibility and liquidity | Long-term market exposure |
| Reinvestment risk | Generally higher because proceeds may need to be reinvested sooner | Generally lower for the amount locked in |
| Price movement | Generally smaller | Generally larger |
Short-term bonds can offer greater flexibility because the principal becomes available sooner. However, frequent maturity creates reinvestment risk because future investments may earn lower yields.
Long-term bonds can reduce the need to reinvest the same money frequently, but their market prices can be more sensitive to changes in interest rates.
Thus, the two portions are complementary rather than interchangeable.
Bond Barbell Strategy Vs Bond Ladder Strategy
A barbell and a bond ladder both use maturity diversification, but their structures are different.
A barbell portfolio concentrates investments around short- and long-term maturities, while a ladder spreads investments across several maturity dates.
| Factor | Barbell Strategy | Ladder Strategy |
| Maturity structure | Concentrates investments at the short- and long-term ends | Spreads investments across multiple maturity dates |
| Medium-term bonds | Limited or generally excluded | Usually included |
| Main focus | Exposure to two maturity segments | Creating a regular schedule of bond maturities |
| Reinvestment | Mainly arises when short-term bonds mature | Occurs progressively as bonds mature at different intervals |
| Structure | Two-part portfolio | Portfolio with multiple maturity points |
A barbell may be suitable for investors who prefer a clear two-part structure. A ladder may be useful for investors seeking more regular maturity dates and a predictable flow of reinvestment opportunities.
Neither approach automatically produces better returns. The appropriate structure depends on financial goals, liquidity requirements and risk tolerance.
How Interest Rates Affect A Bond Barbell Strategy
Interest rates have a direct impact on bond prices.
Generally, when market interest rates rise, prices of existing fixed-rate bonds fall. When rates decline, existing bond prices can rise.
The effect is usually more significant for longer-duration bonds. This means the long-term side of a barbell may experience greater market-price fluctuations than the short-term side. At the same time, if a short-term bond matures during a higher-rate environment, its proceeds may be reinvested at the newer rate4
If rates fall, the situation can reverse. Existing long-term bonds with attractive yields may become more valuable, while maturing short-term investments may have to be reinvested at lower rates. Thus, a barbell distributes interest-rate exposure but does not remove it.
How To Build A Bond Barbell Strategy
Investors can follow a practical process when creating a bond portfolio diversification strategy:
1. Identify the objective: Determine whether the money is intended for income, capital preservation or a future financial goal.
2. Estimate liquidity needs: Identify how much money may be required in the near term.
3. Choose the allocation: Decide how much to place in short- and long-term bonds. Percentages should remain illustrative rather than universal.5
4. Check issuer and credit rating: Assess the issuer's ability to repay principal and interest.
5. Compare coupon rates and YTMs: Coupon shows the stated interest payment, while YTM considers the bond's price, cash flows and maturity.
6. Check maturity dates: Make sure maturity dates align with financial requirements.
7. Diversify where appropriate: Avoid excessive concentration in one issuer or sector.
8. Plan reinvestment: Decide what to do when short-term bonds mature.
9. Review periodically: Reassess the portfolio when financial goals or market conditions change.
Key Risks Of A Bond Barbell Strategy
A Bond Barbell Strategy has several risks investors should understand.
Interest-rate risk: Long-term bonds can experience greater price fluctuations when market yields change.
Reinvestment risk: Short-term bonds mature sooner, so their proceeds may have to be reinvested at lower rates.
Credit risk: Corporate and other non-sovereign bonds carry the possibility that the issuer may delay or fail to make interest or principal payments.6
Liquidity risk: Some bonds may not have an active secondary market. An investor selling before maturity may therefore receive a price different from the expected value.
These risks mean that choosing the maturity structure alone is not enough. Investors also need to assess credit quality, yield, liquidity and their own financial requirements.
Barbell Vs Bullet Strategy
The barbell vs bullet strategy comparison is another useful distinction.
| Aspect | Bullet Strategy | Barbell Strategy |
| Meaning | Concentrates investments in bonds with similar maturity dates. | Concentrates investments in short-term and long-term bonds, with limited or no exposure to intermediate maturities. |
| Typical structure | Bonds mature around a specific target date. | Portfolio is divided between short- and long-term bonds. |
| Main objective | Match a known future financial requirement. | Balance liquidity from short-term bonds with potentially higher returns from long-term bonds. |
| Example | An investor planning for a major expense in five years may choose bonds maturing around the fifth year. | An investor may allocate part of the portfolio to short-term bonds for liquidity and the rest to long-term bonds for higher income or capital appreciation potential. |
| Interest-rate exposure | Concentrated around the target maturity period. | Exposed to both short- and long-term interest-rate movements. |
| Suitable for | Investors with a clearly defined financial goal and time horizon. | Investors seeking flexibility, regular liquidity, and exposure across different maturity segments. |
| Key consideration | The maturity date should align with the expected date of the financial need. | The allocation between short- and long-term bonds should reflect the investor’s risk tolerance and liquidity requirements. |
| Core principle | Choose the bond maturity based on the purpose of the investment. | Use maturity diversification to balance liquidity and longer-term growth potential. |
Conclusion
At the end, it is concluded that the Bond Barbell Strategy combines short-term and long-term bonds within one portfolio while keeping intermediate maturities limited. Its structure can provide short-term flexibility alongside longer-term fixed-income exposure.
Moreover, it does not remove interest-rate, reinvestment, credit or liquidity risks. The short and long sides also respond differently to changing market conditions.
Before building a barbell portfolio, investors should consider their liquidity requirements, credit quality, financial goals, maturity dates, YTMs and capability to handle price fluctuations. The allocation should be based on individual circumstances rather than a fixed percentage.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


