

Yield To Worst (YTW): Meaning, Calculation And Why Bond Investors Should Track It


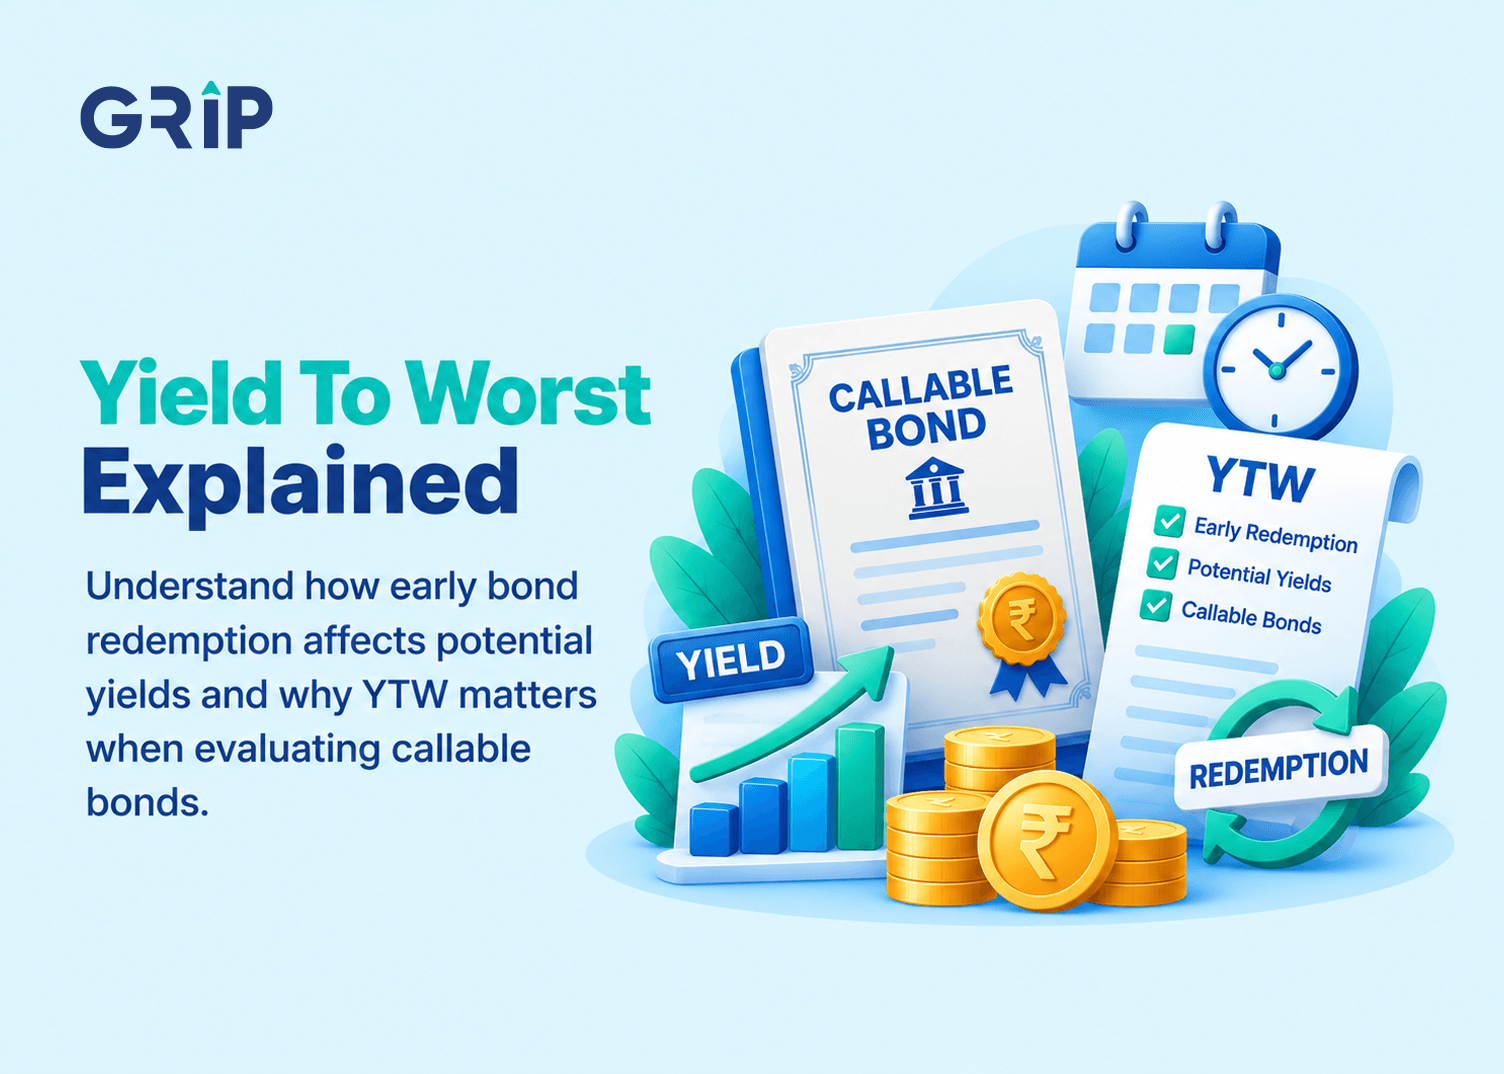
While investing in bonds, investors need to take into account different indicators, just like equities. Even though investment in fixed income securities is subject to a lower risk (as compared to equity and derivatives), if you are choosing bonds or debentures for long-term investment plans, retirement, or any other life goal, it is critical that you look beyond coupons and the credit rating of the bond in which you are interested.
Calculation of bond yields is a critical aspect, as evaluating these can help in predicting real returns from your investment. Depending on the bond’s structure, especially if it includes early redemption options, the actual yield received by investors may differ from initial expectations.
This is particularly relevant for callable bonds, where issuers have the right to redeem bonds before maturity. In such cases, relying solely on traditional yield measures can lead to overestimating returns. This is where Yield to worst YTW becomes essential. It provides investors with a conservative estimate of the minimum yield they can expect, helping them make more informed and risk-aware investment decisions. Let us take account of everything you need to know about YTW, its calculation, and how it can be used for your personal financial management.
What Is Yield To Worst (YTW)?
Yield to Worst Meaning and Definition
In simple terms, the yield to worst meaning bonds refers to the lowest possible yield you can receive from a bond without the issuer defaulting. It assumes that the bond issuer exercises any available early redemption options, such as call provisions, at the most disadvantageous time for the investor.
Instead of assuming that the bond will remain active until its final maturity date, Yield to Worst evaluates all possible scenarios where the bond may be redeemed early. It then selects the lowest yield among those outcomes. This approach ensures that investors understand the minimum potential return they may receive, allowing them to assess the bond more conservatively.
How Does Yield To Worst Work?
YTW works by comparing the potential yield from different permitted redemption outcomes.
For a callable bond, these generally include:
- Yield To Maturity (YTM): The yield an investor may earn if the bond is held until its scheduled maturity date.
- Yield To Call (YTC): The yield an investor may earn if the issuer redeems the bond on a specified call date.
If a bond has multiple call dates, the yield is calculated for each applicable date and call price. The lowest result among these scenarios and the YTM is its YTW.
For example, consider a callable bond with a scheduled maturity of 10 years and multiple possible redemption dates. An investor should not evaluate the bond only on the assumption that it will remain outstanding for the full 10 years. The issuer may exercise its call option earlier, changing the timing and amount of the investor's cash flows.
YTW helps account for these possibilities when assessing the bond's potential yield.
How To Calculate Yield To Worst?
To calculate YTW, investors need to identify the bond's relevant redemption provisions and calculate the yield under each applicable scenario.
The process generally involves the following steps:
- Calculate Yield To Maturity: Determine the yield assuming the bond remains outstanding until its scheduled maturity date.
- Identify Call Dates And Prices: Review the bond documents to identify the dates on which the issuer can redeem the bond and the corresponding redemption prices.
- Calculate Yield To Call: Calculate the yield for each applicable call date using the purchase price, coupon payments, call price and time remaining until redemption.
- Compare The Yields: Compare the YTM with the calculated YTC figures.
- Identify The Lowest Yield: The lowest applicable yield is the bond's Yield To Worst.
The calculation considers the timing and amount of the bond's cash flows, including coupon payments and the principal repayment amount.
For bonds without an issuer call option or other relevant early redemption provisions, YTW will generally be the same as YTM.
Why Investors Should Consider YTW Before Investing
Risk-Adjusted Yield Evaluation
One of the primary benefits of Yield to Worst is that it provides a more accurate measure of risk-adjusted returns. Instead of relying on optimistic projections, investors can evaluate bonds based on the minimum return they are likely to receive. If an investor wishes to have a worst-case scenario, this can be the perfect metric for predicting the returns.
This is especially important when comparing multiple bonds with different features. Among various bond yield risk measures, Yield to Worst stands out because it accounts for early redemption risk and prevents investors from overestimating income potential.
Downside Protection and Better Risk Awareness
Yield to Worst also plays a crucial role in protecting investors from unexpected income reductions. When interest rates fall, issuers are more likely to call existing bonds and refinance them at lower rates. This reduces the investor’s future income. It also plays an important role in diversification planning for a portfolio manager or investor.
Using YTW In Fixed Income Portfolio Decisions
Comparing Bond Opportunities Using YTW
Yield to Worst provides a consistent and reliable basis for comparing different bond opportunities. Two bonds may appear similar based on coupon rates, but their Yield to Worst may differ significantly due to call features.
Risk Management and Portfolio Stability
Yield to Worst also helps investors build more stable and predictable fixed income portfolios. It enables investors to estimate minimum expected income and plan accordingly. If you have a conservative approach as an investor, you should not ignore the YTW aspect while comparing a single bond or carrying out an assessment between mutually exclusive bond investment decisions.
Limitations Of Yield To Worst
While YTW is useful for evaluating callable bonds, it should not be treated as a complete measure of investment risk or a guaranteed return.
Investors should consider the following limitations:
1. Does Not Account For Default: YTW assumes the issuer fulfils its payment obligations. It does not estimate the impact of a missed coupon payment or principal default.
2. Does Not Guarantee Actual Returns: The calculated yield depends on the assumed redemption scenario and scheduled cash flows. Actual returns may differ.
3. Does Not Capture All Market Price Movements: If an investor sells the bond before its maturity or call date, the sale price may be higher or lower than the purchase price.
4. Does Not Eliminate Reinvestment Risk: If the bond is redeemed early, investors may have to reinvest the proceeds at less favourable interest rates.
5. Does Not Account For Every Investor's Tax Position: Taxes, transaction charges and other costs can affect the investor's actual post-tax returns.
Therefore, YTW should be considered alongside credit risk, liquidity, interest rate risk, bond terms and the investor's investment horizon.
Yield To Worst Vs Yield To Maturity Vs Yield To Call
YTW, YTM and YTC are different yield measures that help investors evaluate a bond under different holding and redemption assumptions.
| Parameter | Yield To Worst (YTW) | Yield To Maturity (YTM) | Yield To Call (YTC) |
| Meaning | Lowest calculated yield across applicable redemption scenarios | Yield assuming the bond is held until maturity | Yield assuming the issuer redeems the bond on a specified call date |
| Redemption assumption | Lowest-yield scenario among those considered | Scheduled maturity | Specified early redemption date |
| Relevance | Particularly useful for callable bonds | Useful for evaluating bonds held until maturity | Useful for evaluating callable bonds |
| Key consideration | Considers potential early redemption | Assumes no early redemption | Depends on the call date and call price |
Conclusion
As an investor, you should have clarity about different metrics that you can use to evaluate the effectiveness of your investment. This is a fundamental of portfolio management, personal finance, and long-term investment planning. In many cases, investors consider the coupon and credit rating of a bond before making the investment decision. However, for effective planning, considering YTM along with YTW is quite important.
Yield to Worst is a critical yield measure that helps investors understand the lowest return they may receive from a bond. Unlike Yield to Maturity, it accounts for early redemption scenarios and provides a conservative return estimate. By evaluating Yield to Worst before investing, investors can make better decisions, manage risk more effectively, and build more stable fixed income portfolios.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


