

Crude Oil Prices And Bond Yields In India: What Is The Link?


When crude oil prices rise, the Indian bond yields increase too due to higher inflation linked to oil prices, increased import costs, and expectations of a tighter monetary policy.
However, the relationship between crude oil and bond yields in India is influenced by different factors, including RBI policy, government borrowing, and demand for bonds by investors.
The connection works through a chain of effects, i.e, higher oil prices can increase India's import bill, put pressure on domestic prices and change expectations about interest rates. These developments can influence the yields investors demand from government bonds.
However, the extent of the impact depends on whether the oil-price increase persists and how domestic economic conditions respond.
How Do Crude Oil Prices Affect India?
According to the research published in the July 2025 issue of RBI Bulletin, India imports more than 85% of its crude oil needs from abroad. Therefore, the rise in international prices leads to higher energy costs as well.
For example, importing one million barrels of crude oil at $70 per barrel would cost $70 million. If the price increased to $80 per barrel, the cost of importing the same quantity would rise to $80 million, before freight, insurance and other charges.
The exchange rate adds another layer. The cost of an $80 barrel reaches ?6,800 at ?85 per dollar, and at ?88, it reaches ?7,040 before adding freight, taxes, and other charges.
Alongside, companies may face higher transportation and petroleum costs. They can absorb these increases through lower margins or pass some of the additional costs on to consumers.
Additionally, higher international crude prices do not necessarily cause an immediate or equivalent increase in Indian petrol and diesel prices. The connection between the oil costs and the bond yield is quite determined by how much of the rise in import price reaches the domestic price.
Higher crude prices can also widen India's trade deficit by increasing the value of its oil imports, all else being equal. If the rupee depreciates at the same time, imported energy can become even more expensive. These effects can influence inflation expectations and the outlook for monetary policy, thereby creating a link between global oil prices and domestic borrowing costs.
Why Can Higher Crude Oil Prices Push Indian Bond Yields Higher?
The crude oil and bond yields relationship works through investors’ expectations about future inflation and interest rates.
When inflation rises, a fixed coupon can buy fewer goods. Therefore, the investors may require a higher yield before buying bonds with fixed payments.
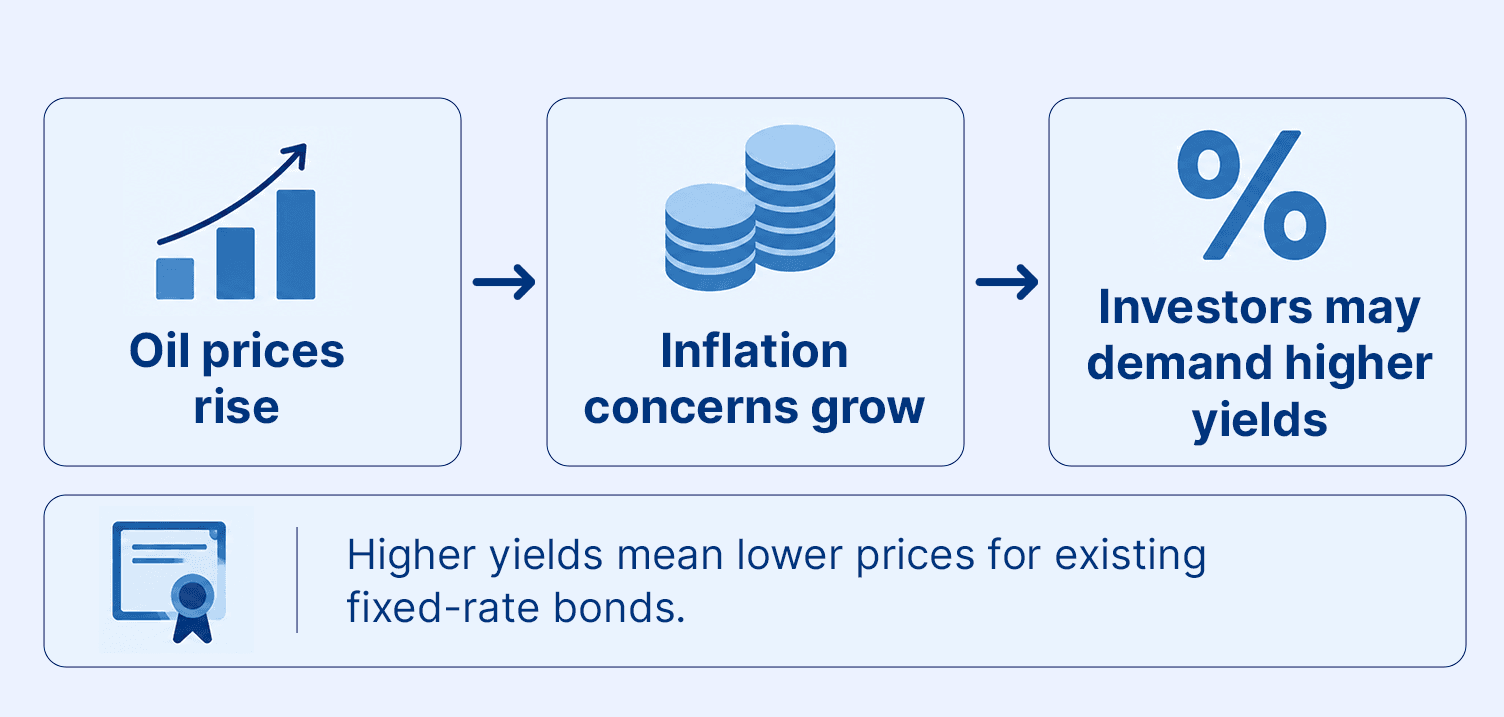
In a scenario of prolonged oil price inflation that reduces the possibility of rate cuts from the RBI, it may also cause investors to review the appeal of existing bonds, as bond prices may continue to decline until the yield offered to new investors becomes competitive again.
The RBI recognises expected inflation, market liquidity and policy interest rates as important influences on G-Sec prices.
A Simple Bond Example
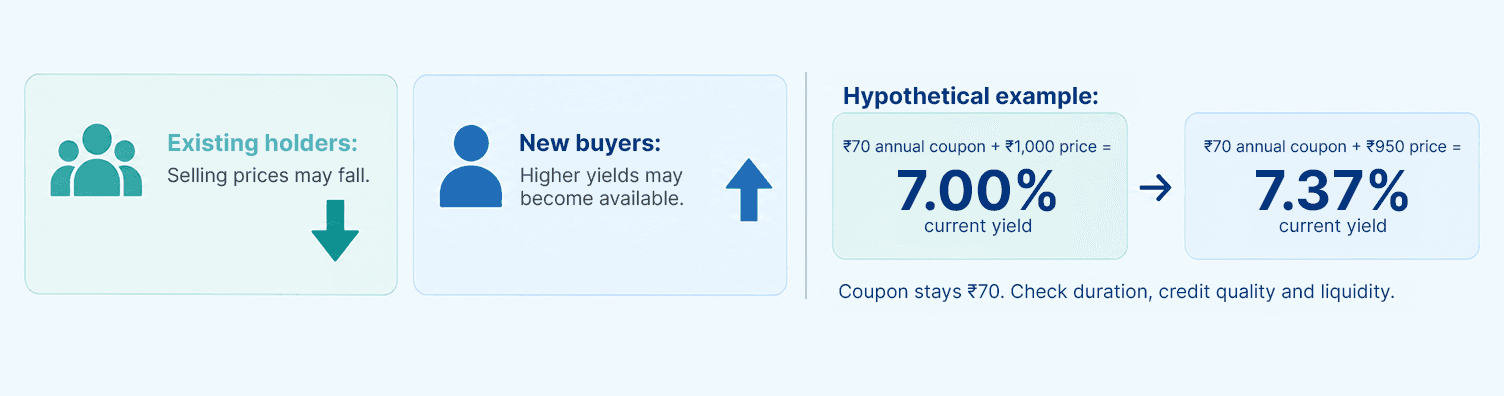
Suppose a bond has a face value of INR 1,000 and pays INR 70 annually. At a market price of INR 1,000, its current yield is 7%.
If its price falls to INR 950, its current yield becomes:
INR 70 ÷ INR 950 × 100 = 7.37%.
The annual coupon remains INR 70. Yield to maturity additionally considers the redemption payment and remaining tenure.
The example here illustrates how a bond's yield can rise when its market price falls. If investors expect persistent oil-driven inflation to push interest rates higher, they may demand greater returns from existing bonds, putting downward pressure on prices. However, the outcome depends on the broader market environment. It does not mean every oil-price increase produces a predictable bond-price decline. Strong demand for government securities or expectations of weaker economic growth can offset inflation concerns.
Crude Oil And Indian Government Bond Yields In 2026
Actual observations help explain the relationship between crude oil and bond yields in India without treating it as a fixed rule.
Brent Crude Price Vs India 10-Year G-Sec Yield
Bank of Baroda Research's July 2026 market tables provide the following paired observations, citing Bloomberg data.
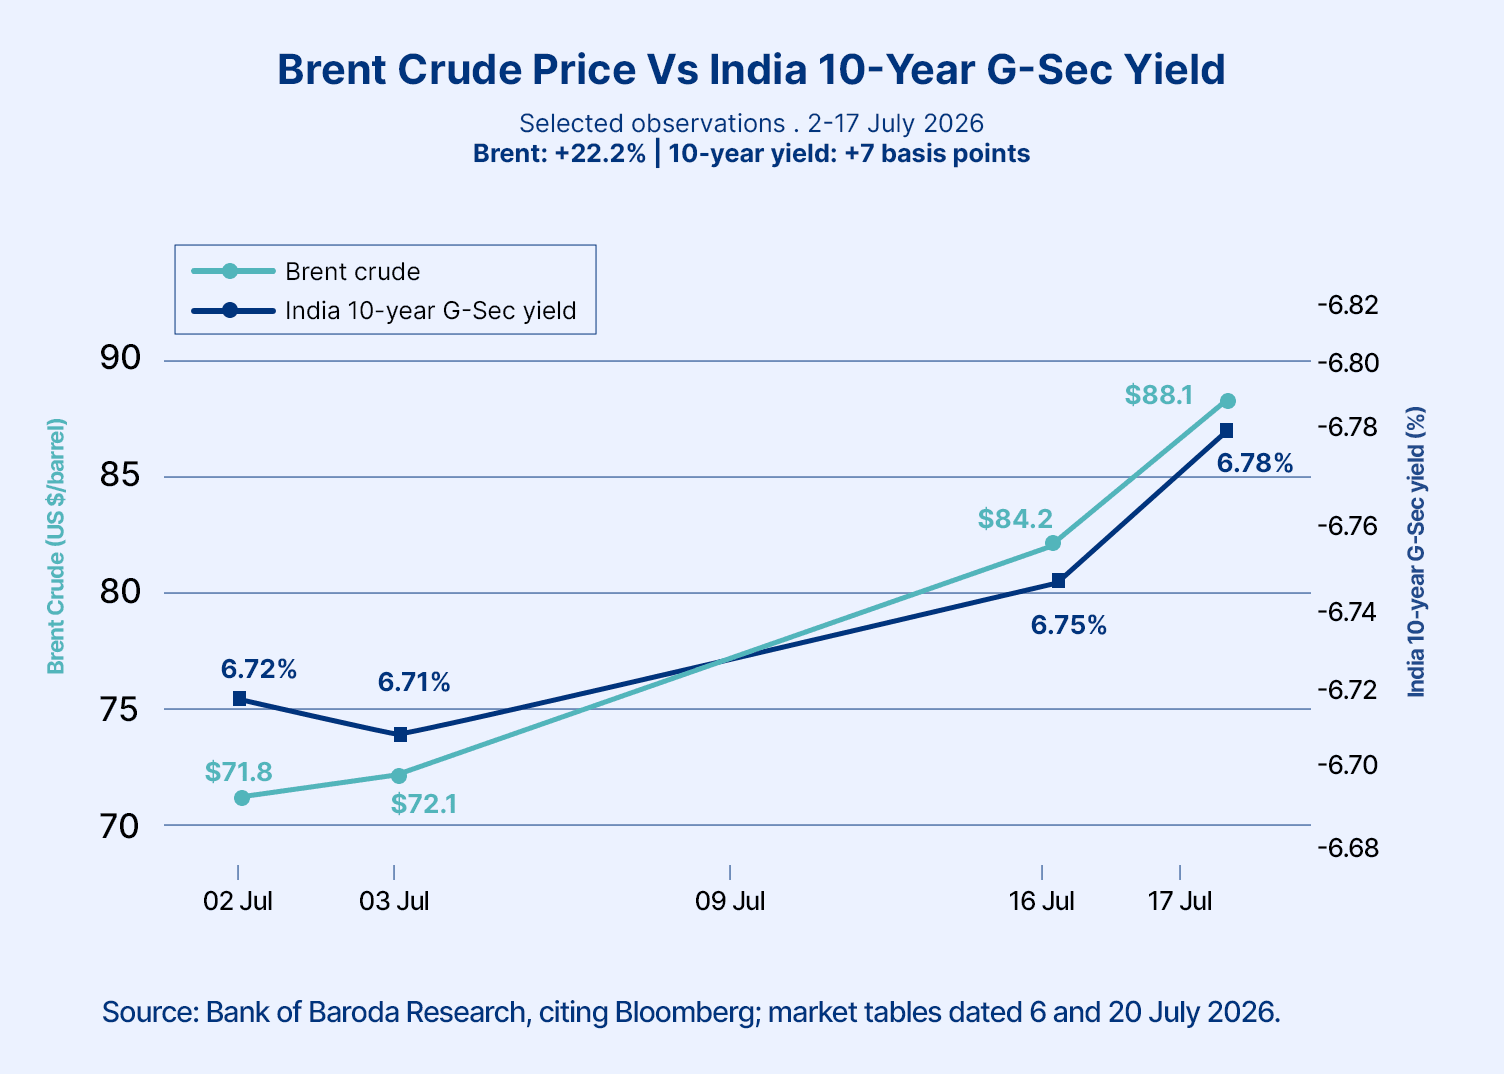
Note: The chart illustrates co-movement, not causation. Similar movements do not establish that crude oil prices caused a particular change in Indian G-Sec yields. RBI policy, inflation, government borrowing, investor demand and global yields can strengthen or offset the impact.
Date | Brent crude, US$/barrel | India 10-year government bond yield |
2 July 2026 | 71.8 | 6.72% |
3 July 2026 | 72.1 | 6.71% |
16 July 2026 | 84.2 | 6.75% |
17 July 2026 | 88.1 | 6.78% |
Source: Bank of Baroda Research, citing Bloomberg.
- Between 3 and 17 July, Brent crude increased by approximately 22.2%, while the Indian 10-year government bond yield increased by seven basis points. One basis point equals 0.01 percentage point.
- Between 2 and 3 July, however, oil prices rose slightly while the bond yield declined by one basis point.
These observations show that crude oil prices and Indian bond yields can move in different directions over short periods. The figures alone cannot establish that oil prices caused the changes in bond yields. Hence, other factors including domestic liquidity, investor demand, inflation expectations and global market conditions may also have influenced the movements.
What Other Factors Move Indian Bond Yields?
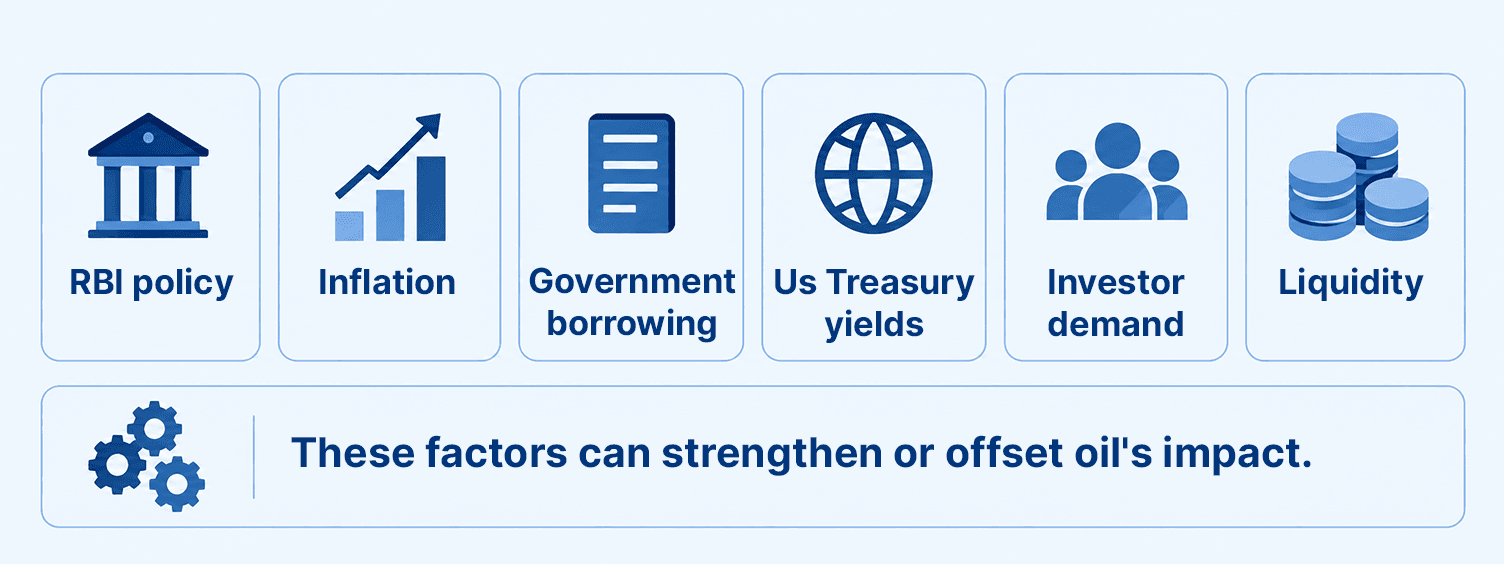
A useful bond yields analysis must account for forces that can reinforce or offset an oil-price shock. Some of the factors influencing India bond yields involve:
1. RBI Policy Expectations: Expectations of rate cuts can support bond prices, while expectations of higher interest rates can weaken them.
2. Government Borrowing: Additional bond supply can push yields higher if demand does not increase sufficiently.
3. Domestic Inflation: Food-price changes can alter inflation expectations even when crude prices remain stable.
4. Global Yields: Higher US Treasury yields can change the relative attractiveness of Indian debt to overseas investors.
5. Institutional Demand: Purchases by banks, insurers and pension funds can support bond prices.
6. RBI Bond Purchases: Purchases of government securities can add demand and influence market liquidity.
The RBI considers domestic supply and demand, international bond-market developments, and its policy measures as important influences on bond prices.
Note that these factors can interact. For example, higher crude prices may increase inflation concerns, but strong domestic demand for government securities can limit the resulting rise in yields. On the other hand, increased government borrowing or rising global yields may add pressure even if oil prices remain stable.
Thus, even when there is a rise in oil prices, the yields for Indian bond markets may drop if some other positive factors come into play. Investors assessing crude oil and bond yields should consider the wider economic context rather than attributing every market movement to energy prices.
Crude Oil, Inflation And The RBI
The inflation channel helps explain the oil prices and Indian bonds relationship, but the extent and persistence of the impact matter.
A study published in the RBI Bulletin in July 2025 found that a 10% increase in global crude oil prices could raise India's headline inflation by approximately 20 basis points. Note that this is a research estimate, and not a guaranteed outcome following every oil-price shock.
Temporary Versus Persistent Increases
A short-lived supply disruption may reverse before businesses broadly adjust their prices. If inflation expectations remain contained, an immediate monetary policy response may be unnecessary.
A sustained increase creates a different challenge. Repeated increases in transport and input costs can encourage businesses to raise selling prices. Households may then expect further inflation, potentially increasing pressure for higher wages.
The RBI must assess these effects alongside economic growth. Raising interest rates cannot restore disrupted oil supplies, but it can restrain demand and broader inflation pressures.
The RBI's response can therefore differ depending on the nature of the shock. If higher oil prices are temporary and inflation expectations remain stable, the central bank may look through some of the immediate price pressure. If the increase persists and begins affecting broader inflation, the RBI may need to reconsider its policy stance.
For crude oil prices and government bonds, the key question is whether the oil shock changes the expected path of interest rates.
What Does Rising Crude Oil Mean For Bond Investors?
Existing fixed-rate bondholders may face lower selling prices when yields rise. Their contractual coupon payments remain unchanged, provided the issuer continues making payments as scheduled.
New buyers may find higher yields, but they should check whether these reflect changes in interest rates, deteriorating credit quality or poor liquidity.
Duration measures a bond's sensitivity to changes in yields. Hypothetically, a bond with a modified duration of six could lose approximately 3% of its market value if its yield rises by 0.50 percentage point. This estimate assumes other factors remain constant and ignores convexity.
Investors in oil prices and G-Secs should distinguish temporary market-price losses from the payments due at maturity. For corporate bonds, they must also assess the issuer's ability to repay.
Moreover, longer-duration bonds generally experience larger price changes than shorter-duration bonds for the same change in yield. However, maturity alone does not determine sensitivity. Coupon rates, payment schedules and the bond's duration also matter. These differences can contribute to bond market volatility in India, as changes in interest rates and market yields affect bond prices differently depending on their characteristics.
Investors should also distinguish between interest-rate risk and credit risk. Rising yields can reduce a bond's market price, while a deterioration in an issuer's creditworthiness can create additional losses, particularly if the investor needs to sell before maturity.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


