

How US Fed Rate Decisions Affect Indian Bonds In 2026


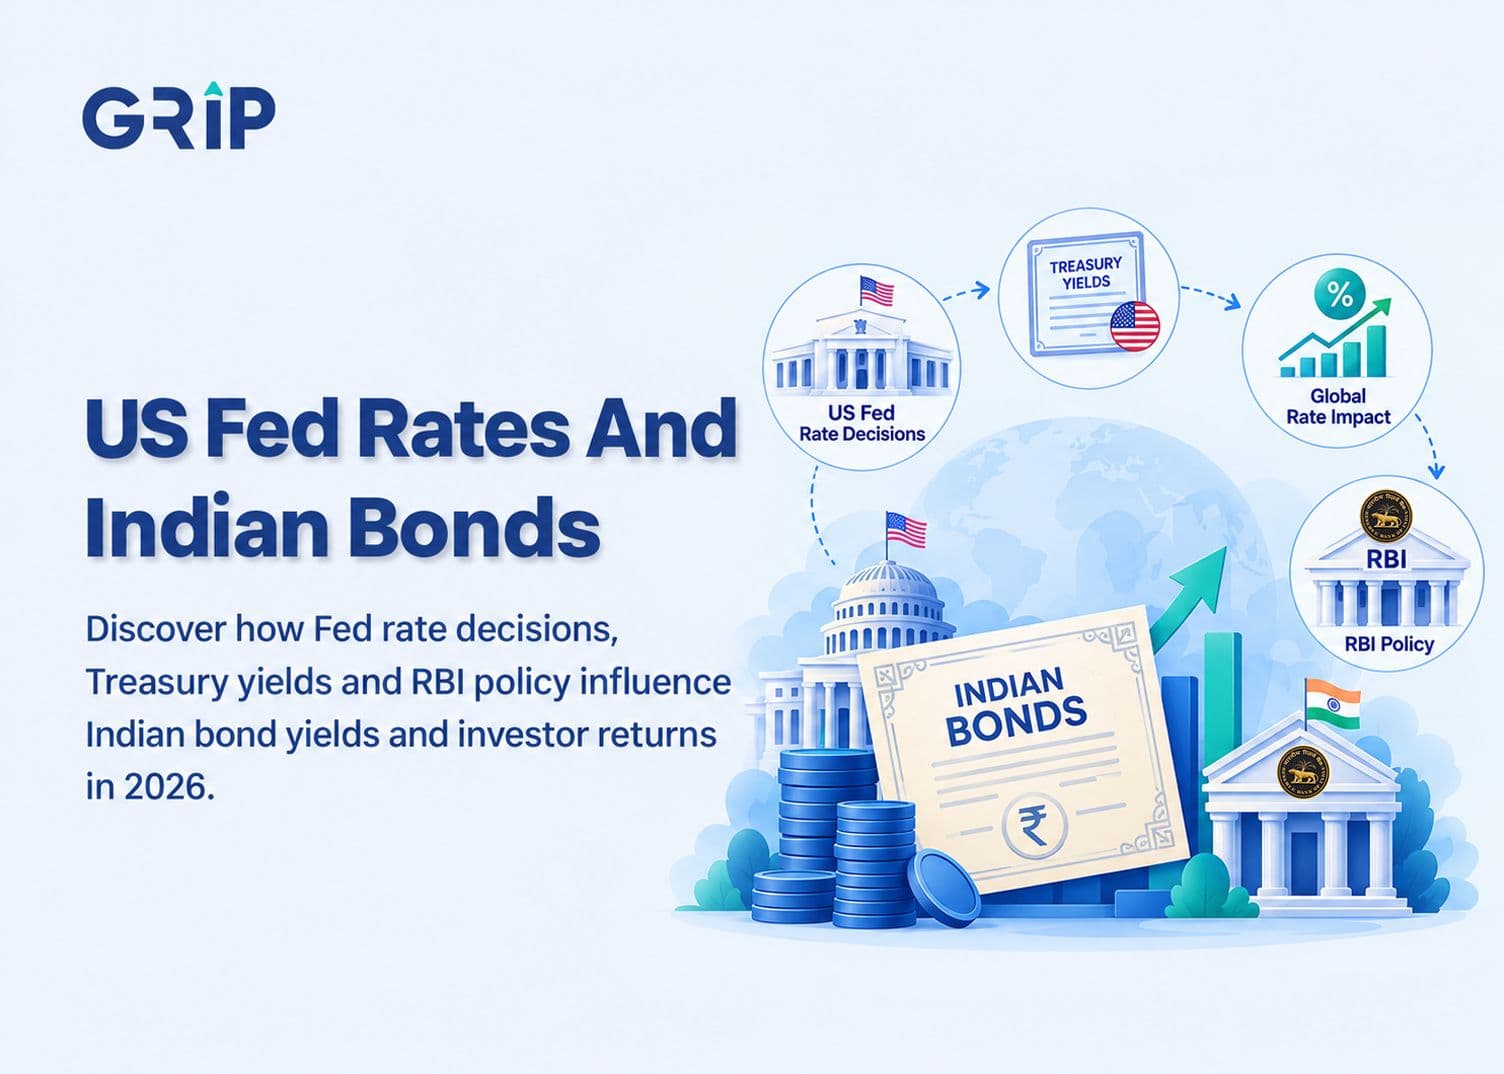
The US Fed rate decisions can impact the yield on Indian bonds through changes in US Treasury yields, foreign investments and fluctuations in the rupee. The overall outcome also depends on Indian inflation, RBI policy and the demand for bonds within India.
The Fed announced an increase of 25 basis points in its policy-rate target range from its previous level to a new rate in the range of 3.75% to 4.00% on 16 September 2026. On the other hand, the RBI’s repo rate stood at 5.50% as on 7 October 2026.
For investors, the US Fed and Indian bonds relationship matters because changing yields affect a bond’s trading price and the return available to a new buyer. Understanding those effects begin with the channels through which US monetary policy reaches India’s bond market.
How Does The US Fed Affect Indian Bonds?
The relationship between the US Fed and Indian bonds can be established through the channels of investment flows, currency fluctuations, and interest rate predictions. Nonetheless, the US Fed is not the reason for the determination of Indian bond yields. Other factors that play a role in the determination include domestic inflation, RBI policy, government borrowing, and demand in the Indian economy at large.
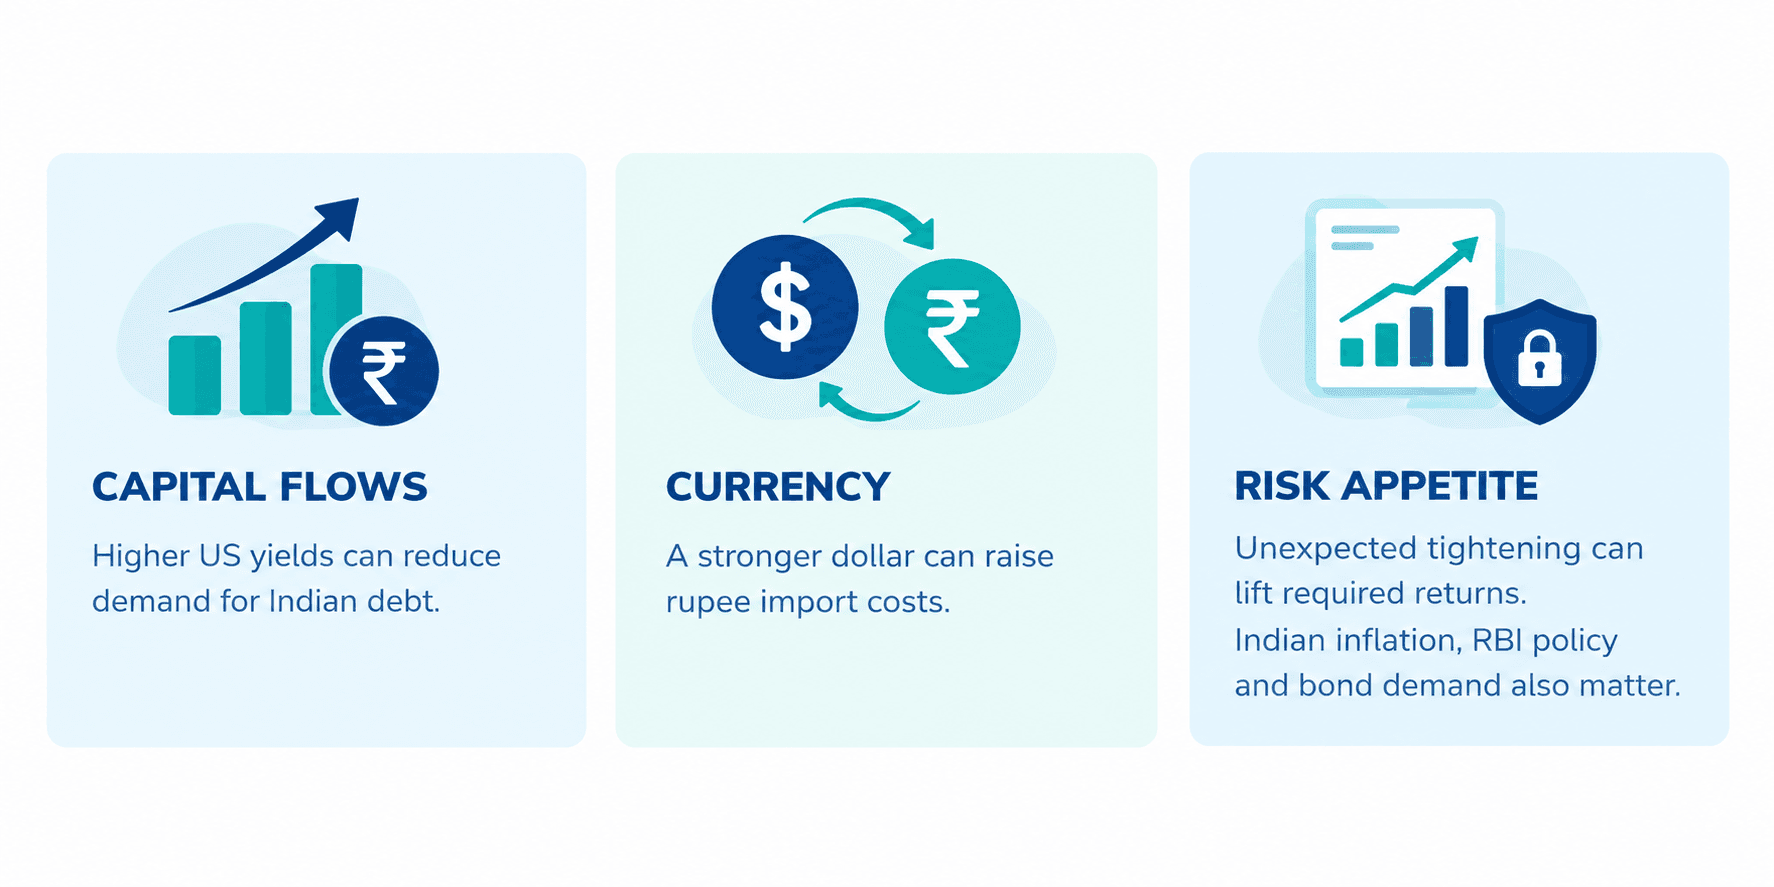
The relationship between US Fed and India bonds operates through three main channels:
- Investment Flows: Higher US yields can attract investors towards dollar-denominated assets, potentially reducing demand for Indian bonds. If foreign investors sell Indian government bonds, their prices may fall and their yields may rise, all else being equal.
- Currency Movements: A strong dollar can weaken the rupee and increase the cost of dollar-denominated imports. If depreciation raises imported inflation, it could influence expectations about RBI policy and put additional pressure on Indian bond yields.
- Risk Appetite: Unexpected monetary tightening can make investors more cautious about emerging markets. They may demand higher returns to compensate for currency, liquidity and other investment risks, potentially increasing the yields required on Indian debt.
Research by the Federal Reserve highlights that the reasons behind the rise of US interest rates make a difference. Rate increases associated with stronger economic growth can affect emerging markets differently from increases driven by inflation concerns or unexpected monetary tightening.
Hypothetical Example
Suppose US interest rates rise while inflation in India declines and domestic institutions increase their purchases of government bonds. Higher US yields could put upward pressure on Indian bond yields by making dollar-denominated assets more attractive. However, falling domestic inflation and stronger demand for Indian government bonds could exert downward pressure. The eventual movement would depend on which factors have the greater influence.
Why Do US Treasury Yields Matter For Indian Bonds?
Treasury yields represent the returns investors require to hold US government debt at prevailing market prices. Investors compare these yields with those available in other countries when evaluating investment opportunities.
While the Fed provides a range of short-term interest rates, the 10-year Treasury yield reflects the expected interest rates and inflation and economic conditions in the future. It is also influenced by factors such as government debt supply and the compensation investors require for holding longer-term securities. Consequently, the 10-year yield can change before a Fed announcement or move in a different direction from the policy rate.
A Hypothetical Yield Comparison
Let’s consider a scenario in which India's 10-year government security (G-Sec) yields 7%, while the US 10-year Treasury yields 4.5%. The yield differential is 250 basis points, where one basis point equals 0.01 percentage points.
Suppose the US Treasury yield increases to 5%, while the Indian G-Sec yield remains at 7%. The differential narrows to 200 basis points.
A narrower yield differential may make Indian bonds less attractive to some foreign investors, all else being equal. However, it does not automatically trigger capital outflows because investors also consider exchange rate movements, hedging costs, liquidity and the risks associated with each market.
An investor purchasing an Indian bond does not necessarily earn the difference between the Indian and US Treasury yields. Currency movements and hedging costs can reduce or eliminate the apparent advantage.
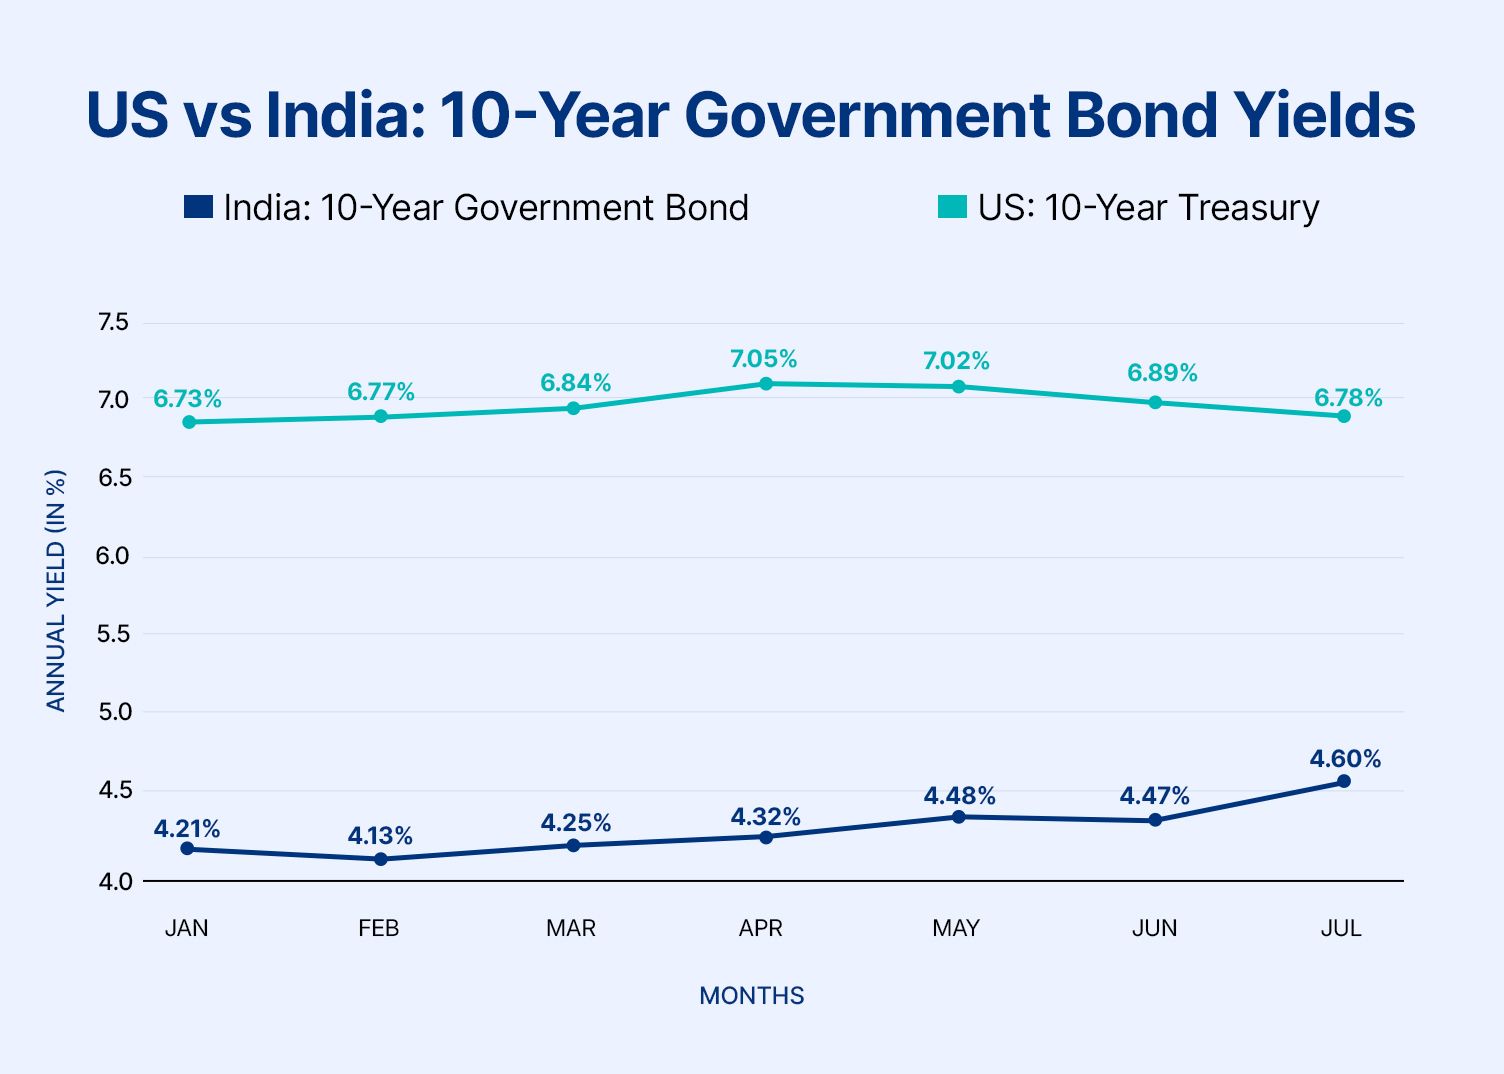
Note: The chart illustrates the movements of US 10-year Treasury yields and Indian 10-year G-Sec yields, and not causation. Similar movements do not establish that US monetary policy caused a particular change in Indian G-Sec yields. Domestic inflation, RBI policy, government borrowing and local bond demand also influence Indian yields.
What Happens To Indian Bonds When The Fed Hikes Rates?
Fed rate hikes could exert upward pressure on Indian government bond yields by boosting returns on assets denominated in U.S. dollars as well as diminishing foreign appetite for rupee-denominated debt. However, an anticipated increase might already be factored into the prevailing prices in the market.
The distinction between expected and unexpected decisions matters. If investors have already priced in a 25-basis-point hike, the announcement may have a limited additional effect. However, if the Fed signals a more aggressive path of future rate increases than markets anticipated, US Treasury yields could rise further and increase pressure on Indian bonds. The actual response depends on market expectations and other economic developments.
Existing Bondholders And New Buyers Face Different Outcomes
Whenever there is a rise in the market yield of a fixed-rate bond, its purchasing price declines. The bond’s coupon payment remains unchanged. A buyer purchasing the bond at a discounted price can obtain a higher yield than someone who purchased it at a higher price, assuming the same payment terms and holding period.
Suppose a bond is priced at INR 1,00,000 and has a modified duration of five years. If its yield rises by 0.50 percentage points, or 50 basis points, its price could decline by approximately 2.5%, assuming other factors remain unchanged. This is a first-order estimate that does not account for convexity or other effects.
The relationship between US monetary policy and Indian bonds is not one-to-one. A 50-basis-point Fed hike does not automatically increase Indian yields by the same amount.
The impact can also differ across maturities. Shorter-term Indian bond yields may respond to changes in expectations about near-term RBI policy, while longer-term yields also reflect expectations about future inflation, economic growth, government borrowing and the compensation investors require for holding longer-maturity securities.
Holding a bond to maturity reduces the importance of interim market price changes, provided the investor does not need to sell early. However, contractual payments still depend on the issuer meeting its obligations.
US Fed And Indian Bonds In 2026
As of 7 October 2026, the following figures provide a dated view of policy settings and the Indian government-bond market:
Measure | Verified figure |
| Fed decision on 16 September 2026 | Target range increased by 25 basis points to 3.75%–4.00% |
| RBI policy rate on 7 October 2026 | Repo rate at 5.50% |
| RBI-listed yield for 6.94% GS 2036 on 6 October 2026 | 7.1969% |
The figures come from the Federal Reserve’s September statement and the RBI’s official rates tables. The policy rates and G-Sec yields measure different things; they are not directly comparable investment returns.1
What These Figures Establish
The figures provide context for understanding the US Fed India bonds relationship, but they do not prove that a particular Fed announcement caused an Indian bond yield movement.
The Fed's policy-rate target range, the RBI's repo rate and the yield on an Indian government security measure different things. The policy rates indicate central bank settings, whereas a G-Sec yield reflects the return investors require to hold that security at its prevailing market price. They should not be treated as directly comparable investment returns.
Assessing Fed policy and G-Sec yields requires separating global influences from Indian inflation, liquidity, government borrowing and expectations about RBI decisions.
Federal Reserve research similarly highlights that emerging-market responses depend on the external monetary policy shock and domestic vulnerabilities.
To evaluate the relationship in 2026, investors should compare movements in US Treasury yields and Indian G-Sec yields around relevant Fed announcements. Changes in foreign investment flows, domestic inflation expectations and RBI policy expectations can provide additional context. These observations can help explain possible transmission channels, but they do not establish causation on their own. Here, knowing India's 10-year bond yield can provide additional context.
Market observations should illustrate the relationship rather than establish a fixed rule or predict an identical response after every announcement.
US Fed Vs RBI: Why Both Matter For Indian Bonds
The Fed influences global financial conditions. The RBI influences domestic monetary conditions through its policy settings and liquidity operations.
US interest rates and Indian bonds can move differently because the two economies face different inflation and growth conditions. Research on international spillovers identifies the receiving country's monetary policy response as an important factor.
For example, rising US Treasury yields may put upward pressure on Indian bond yields. However, falling domestic inflation, stronger demand for government securities or expectations of easier RBI policy could offset some of that pressure. Conversely, persistent domestic inflation or increased government borrowing could keep Indian yields elevated even if US yields decline. The net effect depends on the balance between global and domestic influences.
Hypothetically, Fed rate cuts could ease external pressure on Indian bonds by lowering US yields. However, if Indian inflation remains elevated and investors expect the RBI to maintain or tighten monetary policy, Indian bond yields may not fall by the same amount. A Fed rate cut therefore does not guarantee an increase in Indian bond prices.
Corporate Bonds Also Carry Credit Risk
Corporate bond yields reflect the issuer's creditworthiness and the bond's liquidity, in addition to broader interest rate conditions.
For example, if a corporate bond yields 9% while a comparable government security yields 7%, the yield spread is 200 basis points.
Suppose the G-Sec yield falls to 6.75%, but the corporate bond's spread widens to 250 basis points, the corporate bond yield would then be 9.25%.
The wider spread means investors require greater compensation over the government security's yield. This could reflect higher perceived credit risk, reduced liquidity or other factors affecting the corporate bond. It demonstrates why a fall in government bond yields does not guarantee a fall in every corporate bond yield.
Here, investors should distinguish interest rate risk from credit risk. Changes in government yields can affect a corporate bond's market price, while changes in the issuer's perceived ability to repay can independently affect its credit spread.
What Should Indian Bond Investors Watch?
To assess the US Fed impact on Indian bond market, investors should monitor five major indicators:
1. Fed Decisions and Guidance: Compare announcements with what investors expected and assess whether expectations about future rate decisions have changed.
2. US Treasury Yields: Track longer-term market yields, particularly the 10-year Treasury yield, rather than relying only on the Fed's policy rate.
3. Indian Inflation and RBI Policy: Assess domestic inflation trends and expectations about borrowing costs, which can amplify or offset global pressures.
4. USD/INR and Foreign Debt Flows: Monitor exchange rate movements and changes in foreign investor demand for Indian debt.
5. Government Borrowing and Liquidity: Track the supply of government securities and domestic funding conditions, which can influence yields independently of Fed policy.
Investors should also assess the maturity, duration, credit rating and payment terms of the bonds they hold, along with their potential resale value if they need to exit before maturity.
For example, an investor who may need to sell a bond before maturity should pay particular attention to interest rate risk and potential price fluctuations. Someone planning to hold a bond until maturity should still assess the issuer's ability to meet its payment obligations and whether the investment matches their financial needs.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


