

Money Market Funds In India 2026: How They Work, Returns, Risks And Taxation


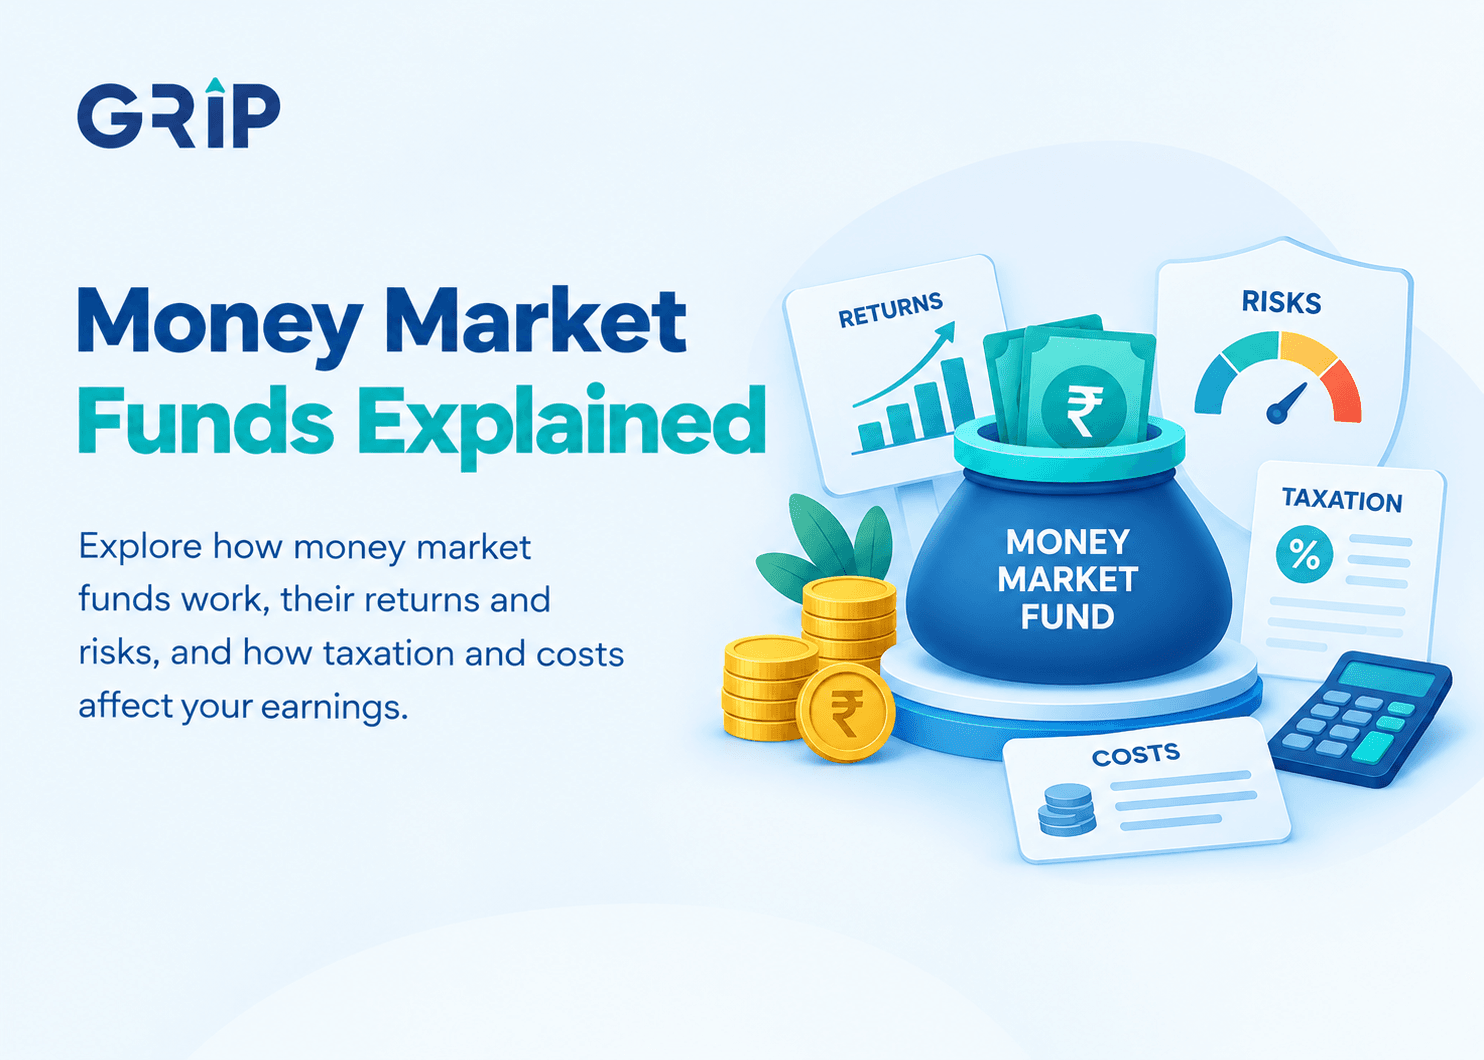
When you have funds to invest in the short term, selecting an investment becomes tough. You may be looking for higher returns than a savings account. But at the same time, you might not like the high fluctuations related to equity investments.
One such investment that you may want to know about is Money Market Funds. They are debt mutual fund schemes that invest in money market instruments.
The shorter tenure of such investments makes them suitable for short-term financial planning needs. However, they are market-linked investments, and hence there is no guarantee of return.
If you are looking at money market fund options in India, knowing how they work is essential. But along with that, comparing their returns, risks, taxation, and costs is equally important.
What Are Money Market Funds?
Money Market Fund Schemes are debt schemes offered by mutual funds. The new classification made by SEBI states that Money Market Funds have a maximum maturity of one year in their instruments. The instruments include Treasury Bills, commercial paper, certificates of deposit, and others.
In simple terms, the definition of a money market fund is quite easy. You simply make an investment in mutual funds that invest the capital of investors in different short-term instruments. The investment is done by professional fund managers.
These funds will help investors save effort in choosing individual short-term securities. Nevertheless, the performance of such a scheme depends on the investment itself.
Suppose you are a young investor named Priya with INR 2 lakhs at hand for a period of nine months. You do not want to invest in direct equities during this time. It becomes possible for you to compare the money market mutual fund with other short-term investments.
Even the global market shows the importance of money market funds. Global money market fund assets were around $13.72 trillion in Q2 2026. They constituted 14% of global regulated open-ended fund assets.
How Do Money Market Funds Generate Returns?
The source of Money Market Fund returns is mainly the securities they hold in their portfolio. These securities earn interest income or are sold at a discount and are redeemed later on.
This is the reason that money market fund returns depend upon short-term interest rates because changes in market interest rates may cause changes in returns from newly purchased securities.
For instance, take a fund that buys a Treasury Bill that is priced at less than its face value at the time of purchase. The price difference will affect the total returns earned by the fund.
Take Rohan as a case study where he invests INR 1 lakh for half a year. He gets an indicative annual yield of 7%. From this, he anticipates earning INR 3,500 in profits. This may not always be the case.
The true results will depend on various factors, which include the portfolio, costs, market performance, among others. Hence, people should never regard an indicative yield as the final return.
International data show the significance of this market. According to ICI, the global money market fund assets stood at $13.72 trillion as at Q2 2026. This rose from $13.47 trillion in Q1 2026.
Money Market Funds Vs Overnight and Liquid Funds
All overnight, liquid, and money market mutual funds have investments with short maturities. But the maturities and rate sensitivity of these investments vary. Appreciating the differences will help you pick an appropriate investment horizon for yourself.
Feature | Overnight Fund | Liquid Fund | Money Market Fund |
Main focus | Overnight securities | Short-term debt and money market securities | Money market instruments |
Maturity profile | One business day | Up to 91 calendar days | Up to one year |
Interest-rate sensitivity | Generally very low | Generally low | Can be higher |
Return driver | Overnight rates | Short-term market yields | Short-term market yields |
Risks of Money Market Funds
Money Market Funds may help avoid any exposure to long-term interest rate risks. Nevertheless, the short-term nature of these funds does not guarantee that the investor will not be exposed to other types of investment risks, such as credit, liquidity, interest rate, and reinvestment risks.
The risks associated with the inability of the issuer to fulfill its debt repayment obligations represent credit risks. Thus, it becomes necessary to consider the quality and diversification of the securities. In addition, interest rate risks may also influence the performance of the investments. For instance, increases in the market yields may decrease the prices of the existing fixed income securities.
Liquidity and the ability to sell securities at reasonable prices may become an issue during turbulent periods. In addition, reinvestment risks may arise in case the maturing securities should be replaced by new securities with lower yields.
Consequently, it is necessary to understand that these funds cannot be viewed as deposits providing a guarantee of returns. Therefore, the following steps should be taken before the investment: analyze the credit quality, diversification, riskometer, and investment strategies of the portfolio.
Taxation and Costs
Money Market Funds could have tax considerations in India depending on the prevailing tax structure in the country. This depends on whether the money market fund scheme is classified as a specified mutual fund.
From the assessment year 2026-27, the specified mutual fund scheme is that which invests in debt and money market instruments in excess of 65% of the total proceeds of the scheme. Tax consideration in this case is covered under section 50AA, where the relevant gains are classified as short-term capital gains.
There may be future changes in tax considerations, so you need to check the latest tax considerations before investing in a money market fund scheme. There are costs involved too, so make sure you consider them too. These include the expense ratio and exit load in the scheme.
Who May Consider Money Market Funds?
Money market mutual funds can be good choices for investors who want to invest in the debt market in the short term. Money market funds can be chosen if the investment horizon is short and you are okay with returns being linked to the market.
For instance, Arjun will have an incoming sum in 8 months, and he has INR 3 lakh that he can use before then. The investor can evaluate the appropriate money market mutual funds based on maturity, credit rating, liquidity, costs, and expected post-tax returns.
On the other hand, these funds may not be ideal for everyone. There might be some investors who would like guaranteed returns and others who are saving money for emergencies.
The investment horizon needs to be the first thing to consider. You should consider the portfolio of the mutual fund, its liquidity, costs, and your tolerance of NAV fluctuations. To know more about this topic, see the guides by Grip on investing in high-interest times and corporate bonds.
Conclusion
In Money Market Funds, investors get access to the short-term debt market and might find these suitable for people wanting market-linked returns for a short period of time.
Returns will be dependent on market yields, portfolio composition, expense ratio, and tax implications. Though shorter maturities lower the risk due to interest rate risk, there will be inherent investment risk. Prior to investing, it will be beneficial to assess your financial objective, investment period, and risk appetite. Going through the scheme papers, portfolio composition, zzuka, and tlooinvrsaa can help you make an informed investment.
Want to know about short-term investment options? It will pay to know about the destination of your money and the risks involved.
FAQs
Want to stay at the top of your finances?
Join the community of 22 lakh+ investors and learn more about Grip Invest, the latest financial knick-knacks, and shenanigans in the world of investing.
Happy Investing!
Disclaimer - Investments in debt securities/municipal debt securities/securitised debt instruments are subject to risks including delay and/ or default in payment. Read all the offer related documents carefully. The investor is requested to take into consideration all the risk factors before the commencement of trading.
This communication is prepared by Grip Broking Private Limited (bearing SEBI Registration No. INZ000312836 and NSE ID 90319) and/or its affiliate/ group company(ies) (together referred to as “Grip”) and the contents of this disclaimer are applicable to this document and any and all written or oral communication(s) made by Grip or its directors, employees, associates, representatives and agents. This communication does not constitute advice relating to investing or otherwise dealing in securities and is not an offer or solicitation for the purchase or sale of any securities. Grip does not guarantee or assure any return on investments and accepts no liability for consequences of any actions taken based on the information provided. For more details, please visit www.gripinvest.in
Registered Address - 106, II F, New Asiatic Building, H Block, Connaught Place, New Delhi 110001


